Why Some Homes Sell Fast — and Others Sit on the Market

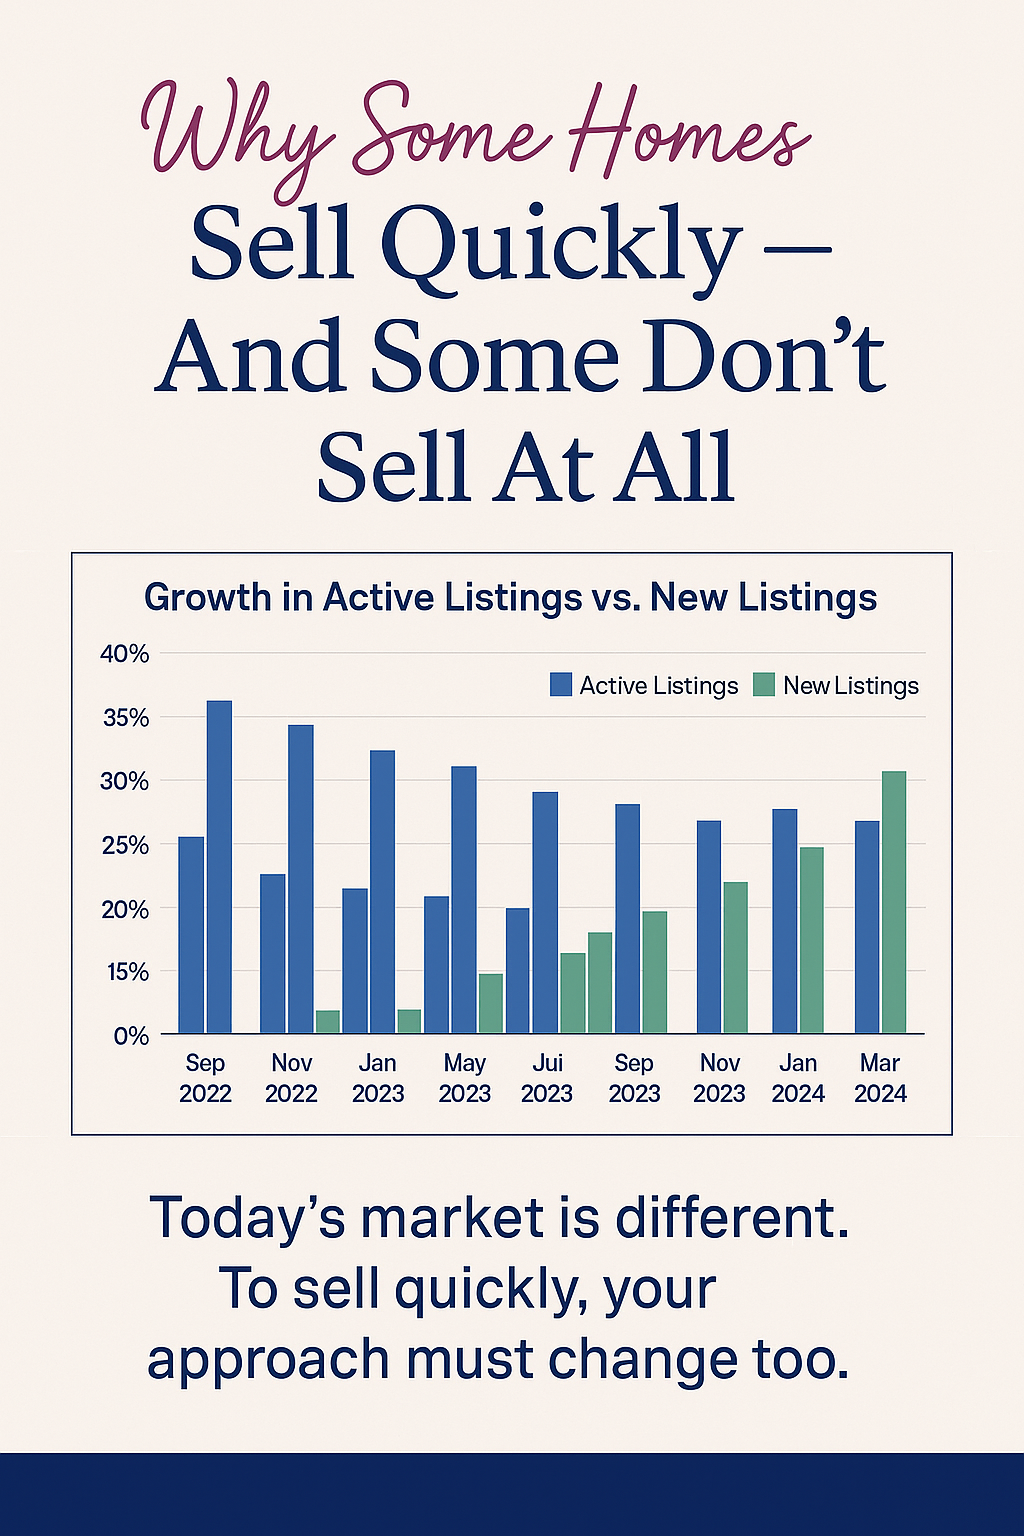
A few years ago, homes were flying off the market. With record-low inventory, nearly anything sold — and fast. But today’s real estate landscape looks different. Inventory is up nearly 20% compared to last year, and in many areas, supply has returned to pre-2020 levels.

So, what does that mean for sellers?
👉 Your home needs to stand out from the moment it hits the market.

🔍 Why Homes Sit on the Market

Most of today’s inventory growth comes from homes that are still active — the ones that haven’t sold yet — rather than new listings. According to Realtor.com, many of these homes are taking longer to sell, which tells us something important:
It’s not just about listing your home — it’s about how you list it.

Common reasons homes linger on the market include:

  • Pricing too high based on old market conditions
  • Skipping essential repairs or updates
  • Poor listing photos or staging
  • Limited showing availability
  • Weak marketing strategies

A few years ago, sellers could list “as-is” and still attract multiple offers. Not anymore. Today’s buyers are choosier, more informed, and have more options.

💡 What Makes a Home Sell Quickly

Selling quickly in this market isn’t about luck — it’s about strategy.
Here’s what successful sellers have in common:

  1. Pricing Realistically – A competitive price based on today’s market, not yesterday’s headlines.
  2. Curb Appeal and Condition – Small upgrades and clean presentation go a long way.
  3. Professional Marketing – High-quality photos, social media visibility, and listing optimization matter.
  4. Accessibility – The easier it is to show, the faster it sells.

Remember: your first few weeks on the market are crucial. That’s when your listing gets the most exposure online. Nail your presentation early, and buyers will act fast.

🤝 Why the Right Agent Makes All the Difference

Working with an experienced REALTOR® means having someone who understands local trends, buyer behavior, and pricing strategy. According to the National Association of REALTORS® (NAR), sellers who work with agents are twice as likely to get an offer within a month compared to those who list on their own.

An expert agent will:

  • Recommend the right listing price using local comparable sales
  • Help you prep and stage for maximum impact
  • Use professional marketing that reaches buyers where they’re searching

✅ Bottom Line

Even with more homes for sale, your property can still sell quickly — if it’s priced right, presented beautifully, and marketed strategically.

If you’re thinking about selling in Hampton Roads, Chesapeake, or Newport News, let’s connect! I’ll help you position your home to attract attention — and offers — from day one.

✨ If you’re looking to sell, call Michele! If you’re looking to acquire — I’m your hire! ✨

Michele Salyer, REALTOR®
Salyer Wilmoth Homes | A Better Way Realty
📞 7575023671 | 🌐 www.salyerwilmothhomes.com

Aug. 12, 2026

What Happens After Accepting an Offer? Hampton Roads Seller Timeline

TL;DR

After accepting an offer on your Hampton Roads home, expect a roughly 30- to 45-day contract-to-close process that typically includes earnest money, the home inspection, appraisal, title work, financing approval, required disclosures, a final walkthrough, and settlement, with the exact timing determined by your contract, the buyer’s financing, and how smoothly each contingency is resolved.

What Happens After a Seller Accepts an Offer in Hampton Roads?

Accepting an offer is an exciting milestone, but it is not the end of the selling process. Once both parties sign the purchase agreement, the contract is ratified and a structured series of deadlines, contingencies, inspections, third-party reviews, and closing preparations begins.

For most Hampton Roads sellers, the contract-to-close period takes approximately 30 to 45 days, although the timeline can vary depending on the buyer’s loan type, appraisal, inspection negotiations, title issues, and the specific terms of the contract.

Here is what I typically walk my sellers through once the contract is signed.

Days 1–3: Earnest Money and Contract Ratification

Once both the buyer and seller have signed the agreement, the contract is officially ratified.

The buyer’s earnest money deposit is generally due shortly afterward according to the deadline established in the contract. The funds are placed into an escrow account, usually held by a title company, settlement company, or brokerage, and are later credited toward the buyer’s closing costs or down payment at settlement.

At this point, one of the most important things I do for my sellers is calendar every contractual deadline. Inspection periods, financing deadlines, appraisal requirements, and settlement dates all matter. Missing one of these deadlines can create unnecessary complications during the transaction.

Days 5–12: The Home Inspection

Many Virginia purchase contracts include a home inspection contingency.

During the inspection period, the buyer hires a licensed home inspector to evaluate the home’s major systems and overall condition. Depending on the results and the language of the contract, the buyer may request repairs, ask for a credit toward closing costs, negotiate a price adjustment, or accept the property without requesting changes.

As the seller, you may have the opportunity to negotiate those requests rather than automatically agreeing to everything.

  • This is where preparation before listing can make a significant difference. Sellers of properties with older systems, previous repairs, crawl-space concerns, or deferred maintenance may want to review my guide to selling an older home in Norfolk and preparing it before listing, because many of the same condition and documentation questions buyers raise before making an offer can resurface during the inspection period.

Some inspection findings are relatively minor, while others may affect the buyer’s willingness or ability to move forward. I help my sellers evaluate which requests are reasonable, which ones may be worth negotiating, and which ones may not justify changing the terms of the sale.

Days 7–21: The Appraisal

If the buyer is financing the purchase, their lender will usually order an appraisal.

A licensed appraiser evaluates the property and provides an opinion of its market value. Because the lender bases the loan on the appraised value rather than simply the agreed-upon purchase price, this can become one of the most important stages of the transaction.

If the home appraises at or above the contract price, the transaction can generally continue as planned.

If the appraisal comes in below the offer price, however, the seller and buyer may need to make another important decision. They might renegotiate the purchase price, divide the difference, adjust the financing, have the buyer bring additional approved funds to closing, or pursue another option permitted by the contract. I break those possibilities down more fully in what happens when a Virginia home appraises below the offer price.

This can be especially relevant in Hampton Roads, where VA financing is common. VA-financed purchases have their own appraisal requirements and procedures, so sellers should not automatically view a slightly different appraisal timeline as a warning sign.

Days 10–25: Title Search and Title Work

While inspections and the appraisal are underway, the settlement or title company generally begins reviewing the property’s title history.

The purpose of the title search is to identify anything that could interfere with the transfer of clear ownership, including unpaid liens, judgments, easements, recording errors, or other claims affecting the property.

As the seller, you are generally expected to be able to transfer clear title at settlement according to the terms of the contract.

Many title issues can be resolved without derailing a transaction, but discovering an issue early matters. When something does appear, I coordinate with the settlement or title company so my sellers understand what needs to happen before closing.

The buyer’s lender will typically require lender’s title insurance. A buyer may also choose to obtain an owner’s title insurance policy for additional protection.

Days 15–30: Financing Contingency and Loan Approval

The buyer’s mortgage is being processed at the same time as the inspection, appraisal, and title work.

During underwriting, the lender reviews the buyer’s income, assets, credit, employment, debt obligations, property information, and other documentation needed to approve the loan.

If the contract contains a financing contingency, the buyer must satisfy the requirements of that contingency within the time provided by the agreement.

Even a buyer who was preapproved can encounter a lending problem before settlement, which is why sellers should understand that a financing issue does not automatically tell you whether the transaction is over or what happens to the earnest-money deposit. If financing becomes uncertain, my guide to what happens if the buyer’s financing falls through before closing explains the factors that may determine whether the parties can preserve the transaction or need to consider their contractual options.

A buyer using VA or FHA financing may also have additional loan and appraisal requirements compared with a conventional borrower. These financing types are common throughout Hampton Roads, particularly because of the region’s large military community.

Before settlement, buyers using mortgage financing generally receive a Closing Disclosure detailing their final loan terms and costs. Sellers receive their own settlement documentation outlining proceeds and transaction expenses.

Seller Disclosures and Other Property Requirements

Virginia sellers may have disclosure obligations depending on the property and circumstances.

Virginia’s residential property disclosure system generally places substantial responsibility on buyers to investigate the property rather than treating the seller’s disclosure as a comprehensive warranty of its condition. Because the requirements and acknowledgment forms can be easy to misunderstand, sellers and buyers who want a deeper explanation can review my guide to Virginia’s 2026 Residential Property Disclosure Statement, including some of the due-diligence issues especially relevant in Coastal Virginia.

Homes constructed before 1978 may also be subject to federal lead-based paint disclosure requirements.

If the home is located within a homeowners association or property owners association, additional association documents may be required. Because obtaining those documents can sometimes take time, it is important to begin the process early rather than waiting until closing is approaching.

Your particular transaction may involve additional requirements, so the ratified contract and guidance from the appropriate legal, settlement, or other professional should always control.

The Final Walkthrough

The buyer generally conducts a final walkthrough shortly before settlement, often within the last 24 to 48 hours.

The final walkthrough is not intended to be another full home inspection. Instead, the buyer is confirming that the property remains in the agreed-upon condition, negotiated repairs have been completed, included fixtures or items remain in place, and no significant new problems have developed since the inspection.

I recommend having the home completely ready for the new owners before the walkthrough rather than waiting until the morning of closing to finish moving or cleaning.

A smooth walkthrough helps prevent last-minute disputes when everyone should be preparing to complete the transaction.

Closing Day: Settlement

Settlement is the final stage of the transaction.

In Virginia, closings are generally handled by a licensed settlement agent, title company, or real estate attorney. The required documents are signed, funds are transferred and disbursed, and the deed is recorded.

Once the transaction has been completed according to the contract and settlement requirements, ownership transfers to the buyer and the keys are released.

For sellers, this is the moment when weeks of inspections, paperwork, negotiations, financing, and deadline management finally come together.

If you have ever wondered what is happening on the buyer’s side while all of this is taking place, my step-by-step guide to buying a home in Chesapeake, Norfolk, and Virginia Beach walks through the process from preapproval and making an offer through inspections, financing, and closing day.

How Long Does the Contract-to-Close Process Take in Hampton Roads?

A typical Hampton Roads transaction takes approximately 30 to 45 days from contract ratification to settlement, but there is no universal timeline.

A straightforward cash transaction may sometimes close much faster. A financed purchase may require additional time for underwriting and appraisal. VA and FHA transactions can also involve additional requirements that affect timing.

Inspection negotiations, title problems, HOA documentation, appraisal disputes, buyer financing issues, or other unexpected circumstances can extend the process.

The most important dates are not general market averages—they are the deadlines written into your individual ratified contract.

That is why I track the timeline closely for my sellers from the day the offer is accepted through the day the deed is recorded.

What Hampton Roads Sellers Should Keep in Mind

Once your home goes under contract, several parts of the transaction are happening simultaneously.

The buyer may be completing inspections while the lender orders the appraisal. The settlement company may already be reviewing title while the lender continues underwriting. At the same time, repair negotiations, HOA documents, seller paperwork, and moving preparations may all need attention.

A good contract-to-close process is less about waiting for settlement day and more about managing each deadline before it becomes a problem.

Understanding what comes next allows you to make informed decisions, prepare for potential negotiations, and avoid unnecessary surprises during the final weeks of your home sale.

Frequently Asked Questions

How long does it take to close on a house in Hampton Roads after accepting an offer?

Most Hampton Roads home sales close approximately 30 to 45 days after contract ratification, although the exact timeline depends on the purchase agreement, financing type, appraisal, inspection, title work, and other contingencies. Cash transactions may close considerably faster, while some financed transactions can take longer. Your ratified contract contains the deadlines that ultimately control your specific transaction.

Can a buyer back out after I accept their offer in Virginia?

Yes, a buyer may be able to terminate the transaction if the contract gives them a valid right to do so, such as through an inspection, appraisal, financing, or another contingency. Whether the buyer can terminate and what happens to the earnest money depends on the wording of the ratified contract and whether the required procedures and deadlines were followed. If you are preparing to sell in Hampton Roads, I can help you understand the practical impact of the contingencies in an offer before you accept it.

What repairs am I required to make as a seller in Virginia?

Virginia sellers are not automatically required to agree to every repair requested after an inspection. Your obligations depend on the purchase agreement and anything you later agree to in writing during inspection negotiations. Once a repair or credit becomes part of a signed agreement, however, it can become a contractual obligation. Having an experienced agent help you evaluate inspection requests can make it easier to determine which items are worth negotiating and which may be better handled another way.

What is a settlement agent in Virginia, and do I need a real estate attorney?

A settlement agent coordinates many of the administrative and financial aspects of closing, including preparing settlement documents, handling funds, coordinating title matters, and recording the deed. Virginia transactions may be handled through appropriately licensed settlement providers or attorneys depending on the circumstances. A separate real estate attorney is not automatically required for every transaction, although either party may choose to consult one. If you are selling a Hampton Roads property, I can help coordinate with your selected settlement provider so the transaction stays organized through closing.

What happens to the earnest money if the deal falls through?

The answer depends on why the transaction ended and what the contract says. If a buyer properly terminates under a valid contingency, the earnest money may generally be returned according to the contract. If a buyer defaults outside of an available contractual right, the seller may have remedies involving the deposit. Seller default can create different consequences. Because earnest money disputes are highly dependent on the specific contract and circumstances, parties should consult the appropriate real estate or legal professional when a dispute occurs.

The Bottom Line

Accepting an offer is the beginning of the contract-to-close process, not the end. The following weeks can involve inspections, appraisal, financing, title work, disclosures, negotiations, the final walkthrough, and settlement, and each step comes with deadlines that can affect whether the transaction reaches the closing table successfully.

This article is provided for general informational purposes and is not legal, tax, lending, or financial advice. Specific transaction questions should be confirmed with the appropriate attorney, tax advisor, lender, settlement agent, or other qualified professional. Equal Housing Opportunity.

If you are selling a home in Hampton Roads and want someone helping you stay ahead of each deadline from contract to closing, call or text Michele Salyer at 757-502-3671 to talk through your next move.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Aug. 11, 2026

Greenbrier Chesapeake: What’s Driving Its Growth

TL;DR

Greenbrier continues to stand out within the Chesapeake real estate market because several advantages are working together at the same time: a central location with access to major Hampton Roads employment corridors, an established concentration of shopping, dining, and everyday conveniences, newer housing opportunities alongside established neighborhoods, and continued interest from buyers looking for their next-step home rather than an entry-level purchase; AIM’s August 2026 market snapshot places the median sale price at approximately $733,000, with five active listings, one new listing in the preceding 30 days, eight sales during the trailing roughly 90-day period, and a median of 48 days on market, suggesting a market where available inventory remains limited relative to the level of buyer interest, but the numbers alone do not determine whether Greenbrier is the right fit—a buyer still needs to compare individual homes, total ownership costs, commute patterns, property condition, new-versus-resale tradeoffs, and how Greenbrier stacks up against other Chesapeake communities before making a decision.

Why Greenbrier Stands Out in the Chesapeake Market

Greenbrier is not a newly discovered part of Chesapeake. It has been one of the city's established residential and commercial corridors for years. What makes the current market interesting is the way its existing infrastructure and location are intersecting with the needs of buyers who are ready for a different type of home.

For some buyers, that means moving from a smaller or first home into a property with more usable space, a different floor plan, newer systems, a garage, additional storage, or a location that makes everyday errands easier. Others are relocating into Hampton Roads and want a Chesapeake address that still provides practical access to employment centers across the region.

Greenbrier's position near I-64 and major Chesapeake roadways is part of that appeal. Buyers commuting toward Norfolk, Virginia Beach, Portsmouth, Suffolk, or other parts of Hampton Roads can evaluate Greenbrier as a central option rather than searching based on city boundaries alone.

That becomes especially relevant for military-connected households. A buyer focused entirely on living as close as possible to Naval Station Norfolk may overlook areas where a somewhat broader search produces a better balance of space and accessibility. Our guide on how to search for more space without losing access to Naval Station Norfolk explores that tradeoff in more detail for buyers deciding how much commute flexibility they are comfortable accepting.

Greenbrier also benefits from something newer neighborhoods cannot immediately recreate: established infrastructure. Shopping, restaurants, services, roads, offices, and residential areas have developed around one another over time. For buyers who want conveniences nearby without giving up a suburban Chesapeake home search, that combination can put Greenbrier high on the list.

What the Greenbrier Market Numbers Show Right Now


The August 2026 market snapshot included in the AIM report shows a relatively tight Greenbrier market.

Market Indicator Greenbrier – August 2026
Median Sale Price $733,000
Median Days on Market 48 days
Active Listings 5
New Listings – Last 30 Days 1
Homes Sold – Trailing ~90 Days 8

Source: Recent Zillow market data cited in the AIM draft, using area-level figures and a trailing approximately 90-day period as of August 2026. Individual property values can vary substantially based on location, condition, size, improvements, lot characteristics, build year, and timing.


Those numbers are more useful when viewed together than individually. Five active listings and only one newly listed property indicate limited choice at the moment captured by the data. Eight sales during the preceding roughly 90 days show that transactions are still occurring despite that limited supply.

The $733,000 median also reinforces an important point: Greenbrier is not necessarily competing for the same buyer as every other part of Chesapeake. Buyers at this price point may be evaluating condition, age, floor-plan functionality, location, maintenance expectations, and long-term flexibility alongside square footage.


That is why two homes with similar asking prices can still represent very different purchases. Our article on why two homes in Chesapeake at the same price can feel completely different is useful if you're trying to understand why list price alone doesn't tell you which property offers the stronger fit.

Why Location Continues to Work in Greenbrier’s Favor

Location is one of Greenbrier's most durable advantages.

It sits within a part of Chesapeake that connects relatively easily to several major Hampton Roads corridors. That can matter for households where two people commute in different directions, buyers relocating without knowing whether their employment location could change later, or military households balancing access to installations with other lifestyle priorities.

But commute decisions should always be property-specific. A route that looks simple on a map may feel very different during weekday traffic, and the difference between two Greenbrier-area addresses can be meaningful depending on where the buyer travels most often.

The same principle applies to shopping and services. Greenbrier's established retail and dining corridor gives buyers access to a concentration of everyday conveniences, but proximity should still be evaluated based on the exact home rather than the neighborhood name alone.


This is one reason area selection should come before simply sorting every Chesapeake listing by price. Different parts of the city can deliver very different ownership experiences even when the numbers look comparable.

New Construction Is Adding Another Layer to Greenbrier Demand

New construction has also contributed to Greenbrier's current momentum.

Some buyers reaching their next home purchase are specifically looking for features that can be easier to find in newer construction: contemporary floor plans, newer building systems, current finishes, energy-efficiency improvements, warranty coverage, larger kitchens, flexible-use spaces, and layouts designed around today's household routines.

Greenbrier's established roads, utilities, commercial infrastructure, and existing residential base can make nearby infill and new-development opportunities especially interesting because buyers are not necessarily choosing between a fully established neighborhood and modern housing. In some cases, they may be able to find elements of both.

That does not automatically make new construction the better purchase.

A newer home may reduce certain immediate maintenance concerns, while an established resale home may offer a larger lot, mature landscaping, a different street setting, completed upgrades, or other features that are difficult to compare on a simple price-per-square-foot basis.

Buyers should look at the entire ownership picture rather than assuming newer means better value.

What Move-Up Buyers Should Actually Compare

A buyer moving into a higher price point often has a clearer idea of what did not work in the previous home.

Maybe storage was limited. Maybe the kitchen and living areas did not flow well. Maybe the yard required too much work—or there was not enough outdoor space. Maybe the commute became harder than expected. Maybe an extra bedroom, first-floor flex room, dedicated office, larger garage, or updated systems have become priorities.

Greenbrier can appeal to buyers working through exactly those questions because the housing search may include both established properties and newer options.

The important thing is not simply to buy a more expensive house. It is to make sure the next home actually solves the problems motivating the move.


That can make comparisons with other Chesapeake communities useful. For example, buyers who like Greenbrier's central, convenience-oriented setting may find a very different ownership experience in Hickory, where larger lots and a more spread-out residential setting can become part of the decision. Reading our buyer’s guide to Hickory in Chesapeake can help clarify whether you value Greenbrier's accessibility more than the additional space and less-dense setting found in other parts of the city.

Total Ownership Cost Matters at Greenbrier’s Price Point

The purchase price is only the starting number.

A Greenbrier buyer should also understand property taxes, homeowners insurance, HOA or condominium fees where applicable, utilities, expected repairs, commuting costs, and the likely maintenance requirements of the particular property.

This becomes increasingly important when comparing a newer property with an established resale home. One may carry a higher purchase price but fewer immediate system replacements. Another may cost less initially but require updates over the first several years.

Taxes also deserve attention early rather than after a buyer is already attached to a property. Our breakdown of property taxes in Chesapeake, Norfolk, and Virginia Beach explains how assessed value and local tax rates can affect the monthly ownership picture when buyers are comparing homes across city lines.

Insurance should be handled the same way. Chesapeake contains properties with different flood and insurance considerations, and buyers should investigate the exact address rather than relying on broad assumptions about Greenbrier or any other part of the city.


The monthly mortgage payment matters, but it is not the complete cost of owning the home.

How Greenbrier Compares With Other Chesapeake Communities

One of the easiest mistakes to make in Chesapeake is treating the city as though every neighborhood offers roughly the same experience.

It does not.

Greenbrier may appeal to buyers prioritizing central access, established shopping and dining corridors, suburban housing, and newer-home opportunities. Other communities may offer more land, different HOA structures, newer planned-community amenities, quieter settings, or different commute patterns.

Sawyers Mill, for example, represents another established Chesapeake option but with a different neighborhood structure and relationship to the Grassfield and Deep Creek sides of the city. If you're still deciding what kind of Chesapeake environment feels right, our guide on how Sawyers Mill compares with other Chesapeake neighborhoods provides a useful side-by-side way to think about commute, amenities, HOA structure, home condition, and long-term ownership fit.

The goal should not be to decide that Greenbrier is objectively “better” than Great Bridge, Deep Creek, Hickory, Sawyers Mill, or another Chesapeake area.


The better question is whether Greenbrier gives you the combination of home, location, convenience, ownership cost, and flexibility that makes the most sense for your plans.

Why Preparation Matters in a Low-Inventory Market

A tight market changes how buyers should prepare.

If only a small number of homes match your preferred location, price point, property type, and condition, waiting until the perfect listing appears before speaking with a lender can put you behind buyers who have already completed those steps.

That does not mean rushing into an offer. It means doing the preparation before the urgency arrives.

Know your comfortable monthly budget. Understand your financing. Decide which property features are non-negotiable and which are preferences. Determine how much work you are willing to take on. Test your commute. Review the total ownership costs.

Then, when an appropriate Greenbrier home becomes available, you can evaluate the property itself instead of scrambling to answer basic financial questions.


This is particularly important for buyers bringing equity from another property because the timing of a sale and purchase can influence offer strategy, financing, and how much flexibility the household actually has.

What Greenbrier’s Growth Means for Buyers and Sellers

For buyers, Greenbrier's current market conditions mean that preparation and property-specific analysis matter more than simply watching listings online.

Limited inventory can make an attractive property feel urgent, but urgency should not replace due diligence. Buyers still need to evaluate condition, comparable sales, total ownership cost, location within Greenbrier, HOA information where applicable, insurance considerations, and whether the property actually solves the needs behind the move.

For sellers, constrained inventory can create an opportunity, but it does not guarantee that every property will command the same result. Condition, presentation, pricing, improvements, street placement, layout, and timing still influence buyer response.


A Greenbrier address creates context. The individual property determines the strategy.

Frequently asked questions

Is Greenbrier a good area to buy a home in Chesapeake in 2026?

Greenbrier may be a strong fit for buyers who value central access within Hampton Roads, established shopping and dining options, a suburban Chesapeake setting, and a mix of established and newer housing opportunities. AIM's August 2026 snapshot showed a median sale price of approximately $733,000, five active listings, and a median of 48 days on market, but whether Greenbrier makes sense for a particular buyer depends on budget, property type, commute, home condition, ownership costs, and long-term plans rather than the neighborhood name alone.

Are there new construction homes available in Greenbrier, Chesapeake?

New construction activity in and around Greenbrier has been one factor contributing to buyer interest, particularly for purchasers looking for modern floor plans, newer systems, current finishes, and lower near-term maintenance expectations. Availability changes, so buyers should compare active new-construction opportunities with resale homes rather than assuming one will automatically offer the better value.

If newer construction is one of your priorities, Michele can help you compare what is currently available with established Greenbrier homes and identify the tradeoffs before you narrow your search.

How does Greenbrier compare with other Chesapeake neighborhoods?

Greenbrier tends to offer a different combination of location, commercial convenience, housing options, and regional access than areas such as Hickory, Deep Creek, Sawyers Mill, or Great Bridge. Other Chesapeake communities may offer larger lots, different neighborhood structures, different commute patterns, or a more spread-out setting, so the strongest comparison depends on what matters most to the buyer.

If you are deciding between Greenbrier and another Chesapeake community, Michele can help you compare the homes, commute, ownership costs, and property-specific tradeoffs side by side rather than choosing based only on price or reputation.

What is driving home prices in Greenbrier, Chesapeake?

The AIM market snapshot points to limited available inventory alongside ongoing sales activity as an important part of the current pricing environment. Greenbrier's established location, nearby amenities, regional accessibility, newer housing opportunities, and continued buyer interest can also contribute to demand. However, individual property values still vary based on condition, size, lot, street location, age, improvements, and the market conditions in place when the home is listed.

Is Greenbrier a practical option for military families relocating to Hampton Roads?

Greenbrier's Chesapeake location can put buyers within reach of multiple employment and military-related destinations across Hampton Roads, but the practicality of the commute depends on the specific installation, work schedule, traffic pattern, and property address. Military buyers using VA financing should also have their financing preparation underway before a competitive listing appears.

If Greenbrier is on your PCS search list, Michele can help you compare it with other Chesapeake and Hampton Roads options based on your actual commute, space needs, financing, and timeline.


Thinking about buying or selling in Greenbrier? A conversation before you're under pressure to make a decision can help you understand what the current market means for your specific home, budget, and timeline.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Posted in Buyer Guides
Aug. 10, 2026

Shore Drive Virginia Beach: Oceanfront Buying Guide

TL;DR

Buying along Shore Drive in Virginia Beach offers access to the Chesapeake Bay, distinct coastal communities, and a lifestyle that feels very different from the main Oceanfront, but buyers need to look beyond the view before making an offer. Flood-zone designations, flood and wind insurance, elevation certificates, Chesapeake Bay Preservation Area restrictions, condo or HOA rules, and limits on future renovations can all affect the true cost and flexibility of owning a property here. The best approach is to evaluate those issues early—before you become attached to a particular home—so you understand not only what you are buying today, but also what it may cost to insure, maintain, renovate, and eventually resell.

Shore Drive, Chic's Beach, and the North End: What You're Actually Buying Into

Shore Drive is not a single neighborhood. The corridor stretches across several distinct coastal communities, including Chesapeake Beach—better known locally as Chic's Beach—Bayfront, Lynnhaven Shores, and nearby areas toward the North End. Buyers will find everything from bayfront condos and townhomes to older cottages, elevated homes, and properties within walking distance of the Chesapeake Bay.

That variety is part of what makes the area appealing, but it also means two homes only a short distance apart can come with very different ownership considerations. A condo near the bay may involve association rules and shared exterior responsibilities, while a detached home closer to tidal water may require more scrutiny of flood elevation, lot restrictions, drainage, and future renovation plans.

The lifestyle is also noticeably different from the Virginia Beach Oceanfront. Shore Drive and Chic's Beach generally have a more residential, neighborhood-oriented atmosphere, with bay access and local restaurants rather than the concentrated resort activity and boardwalk environment associated with the Atlantic Oceanfront. Buyers deciding between the two should think about how they actually want to live day to day, not simply which property photographs better.


If you are comparing Shore Drive with other waterfront or water-adjacent communities around Hampton Roads, our guide to waterfront proximity near Norfolk and Virginia Beach explains some of the broader tradeoffs involving risk, cost, access, and lifestyle. Buyers who like the Chesapeake Bay atmosphere may also find it helpful to compare the area with Ocean View in Norfolk before narrowing their search.

Chesapeake Bay Preservation Area Rules Can Affect What You Do With the Property

One of the more important differences between buying along Shore Drive and buying farther inland is the Chesapeake Bay Preservation Area, or CBPA. Much of the corridor falls within areas subject to additional environmental and site-development requirements designed to protect waterways and sensitive coastal land.

For buyers, this matters because ownership rights and renovation possibilities may not be as simple as looking at the lot size and assuming there is room to expand. Properties near tidal shorelines can fall within Resource Protection Areas, where buffers, vegetation removal, impervious surfaces, additions, decks, and other exterior work may require additional review or approval.

A cottage with room behind it may appear perfect for a future addition, for example, but the site's environmental designation could limit what can actually be built. Buyers who already have renovation plans should investigate those restrictions before closing rather than assuming a permit will be available later.

Coastal construction can also be subject to additional structural and floodplain requirements, particularly in higher-hazard areas. Depending on the property and proposed work, rules may affect elevation, flood-resistant materials, enclosed areas below elevated structures, and other construction details.


Virginia buyers should also understand what sellers are—and are not—required to disclose. Our guide to Virginia's 2026 Residential Property Disclosure Statement provides additional context for buyers evaluating flood, coastal, and property-condition concerns before settlement.

Flood Risk Should Be Part of the Home Search, Not an Afterthought

Flood exposure is one of the most important due-diligence issues along Shore Drive. FEMA Flood Insurance Rate Maps classify properties according to flood risk, and buyers in this part of Virginia Beach may encounter designations such as AE and VE zones. Those classifications can affect lending requirements, insurance costs, construction standards, and long-term ownership expenses.

The key is to check the specific property rather than making assumptions based on the neighborhood. Two homes on the same corridor may have different elevations or flood-zone classifications, and the presence of water nearby does not tell you everything you need to know about the structure itself.

Buyers should review the FEMA map for the address early in the process and then look beyond the map. Road access during tidal flooding, drainage, storm-surge exposure, the building's elevation, and the history of the particular property can all influence how ownership feels in practice.


For a broader citywide explanation, our article on what buyers should know about flood risk in Virginia Beach explains why risk can vary significantly from one part of the city to another.

Understand the Full Insurance Picture Before You Commit

Standard homeowners insurance generally does not cover flooding, which is why coastal buyers need to understand the insurance stack for a property before closing. In certain FEMA-designated Special Flood Hazard Areas, a lender may require flood insurance as a condition of financing.

Flood coverage may also be only one part of the equation. Depending on the property and insurer, coastal homes can involve wind-related deductibles, exclusions, or additional coverage considerations. The goal is not simply to determine whether insurance is available, but to understand what the property's total annual insurance cost may look like before committing to the purchase.


This is why insurance quotes should be requested early during the contract period rather than a few days before settlement. A home may fit comfortably within your purchase-price budget while the combined cost of homeowners, flood, wind, association dues, taxes, and maintenance changes the overall affordability picture.

Why the Elevation Certificate Matters

An elevation certificate documents how a building relates to the property's base flood elevation and can be an important piece of information when evaluating coastal real estate. It may help clarify floodplain compliance and can be relevant when obtaining or pricing flood insurance.

Ask whether the seller, condominium association, surveyor, or local records already have an elevation certificate available. If one exists, review it during due diligence rather than waiting until late in the transaction.

The certificate becomes particularly important when buyers are comparing properties that appear similar on paper. A home's relationship to flood elevation can influence insurance, renovation requirements, and future ownership decisions even when the homes are located within the same general area.

A Shore Drive Due-Diligence Checklist

Before writing an offer, start with the property's FEMA flood-zone designation and determine whether the parcel is subject to Chesapeake Bay Preservation Area restrictions. If the property belongs to a condominium or homeowners association, review the governing documents closely, particularly provisions involving exterior alterations, storm repairs, common areas, insurance responsibilities, and maintenance.

During the contract period, ask for the elevation certificate and obtain homeowners and flood-insurance quotes as early as possible. Buyers planning renovations should also investigate whether their project would require additional coastal, wetlands, CBPA, or building review.


Property taxes, association fees, insurance costs, anticipated maintenance, and coastal construction requirements should all be considered alongside the mortgage payment. Shore Drive can offer an exceptional location, but understanding the complete ownership picture is what allows buyers to compare properties intelligently rather than simply reacting to the view.

Think About Resale Before You Buy

Coastal due diligence is not only about protecting yourself during the purchase. Many of the same characteristics you evaluate today may matter when you eventually sell.

Flood-zone designation, elevation, insurance costs, condominium financial health, association restrictions, storm-damage history, renovation limitations, parking, beach access, and the condition of the structure can all influence how future buyers perceive the property.

This is especially important when comparing a waterfront or bayfront property with a less exposed home nearby. One may offer better views and water access while the other offers lower ownership complexity. There is no universal right answer—the better property is the one whose risks, costs, and benefits fit your goals.

Frequently Asked Questions

Is Shore Drive in Virginia Beach in a flood zone?

Flood risk varies by individual property. Parts of the Shore Drive and Chesapeake Bay corridor fall within FEMA-designated Special Flood Hazard Areas, including AE and VE zones, while other properties may have different classifications. Buyers should check the FEMA map for the exact address and review the property's elevation and other site-specific information rather than assuming every Shore Drive home carries the same level of risk.

Do I need flood insurance when buying a home on Shore Drive?

If the property falls within a FEMA Special Flood Hazard Area and the loan is subject to federal flood-insurance requirements, flood coverage may be required by the lender. Even when it is not mandatory, buyers should remember that standard homeowners insurance does not generally cover flooding.

If you are considering a specific Shore Drive property, Michele can help you identify the questions to raise with your lender and insurance professional early enough to factor those costs into your decision.

Is Shore Drive different from the Virginia Beach Oceanfront?

Yes. Shore Drive and Chic's Beach face the Chesapeake Bay and tend to have a more residential, neighborhood-oriented atmosphere, while the main Virginia Beach Oceanfront is centered around the Atlantic Ocean, resort district, boardwalk, and heavier seasonal tourism.

If you are deciding between the two areas, Michele can help you compare available homes based on your preferred lifestyle, commute, price range, property type, and long-term plans rather than choosing based on location alone.

How does an elevation certificate affect a Shore Drive property?

An elevation certificate records information about the structure's elevation relative to the applicable flood elevation. That information can be relevant to floodplain compliance, insurance evaluation, and certain renovation decisions. Buyers should ask whether an existing certificate is available and review it as part of their overall coastal due diligence.

Are there special renovation rules for homes near the Chesapeake Bay?

Potentially. Properties within Virginia Beach's Chesapeake Bay Preservation Area, particularly those near tidal shorelines, can be subject to additional restrictions involving development, vegetation removal, impervious coverage, additions, decks, and other exterior work. Some projects may require review beyond a standard building permit.

If you are buying with plans to renovate, expand, or substantially alter a Shore Drive property, Michele can help you identify the property-specific questions worth investigating before you commit to the purchase.


Shore Drive can offer a distinctive Chesapeake Bay lifestyle, but coastal properties deserve a more detailed look than the listing photos alone can provide. If you're considering buying along Shore Drive, Chic's Beach, Bayfront, or another Virginia Beach waterfront area, reach out to Michele to compare properties and work through the practical details before you make an offer.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Posted in Buyer Guides
Aug. 4, 2026

Can a Military Spouse Buy a Home While the Service Member Is Away?

TL;DR

A military spouse can buy a home while the service member is deployed, underway, stationed elsewhere, attending training, or otherwise unable to participate in person, but the correct process depends on whether the spouse is purchasing and qualifying independently, whether the service member will be a borrower or owner, whether the household plans to use VA or another type of financing, whose income and assets are needed for approval, whether spouse occupancy satisfies the loan program’s primary-residence requirement, and whether a lender- and settlement-approved power of attorney or remote-signing arrangement will be necessary; before making an offer, the household should coordinate with a military-experienced lender, Virginia settlement professional, and real estate agent to confirm the borrower structure, Certificate of Eligibility, title plan, occupancy, underwriting documents, communication limitations, contract deadlines, inspection strategy, final walkthrough, insurance, wire procedures, and closing authority so the absence of the service member does not create preventable delays or place the earnest-money deposit and purchase at risk.


Can a Military Spouse Purchase a Home Without the Service Member Present?

es. A service member does not necessarily have to be physically present for a military spouse to search for, contract for, finance, and close on a home.

The spouse may be able to purchase independently using their own income, credit, assets, and financing. The Consumer Financial Protection Bureau explains that a spouse is generally not required to co-sign a mortgage obtained in the other spouse’s name when the applicant qualifies independently. A lender may still require signatures connected to ownership, title, or state-law interests even when the spouse is not a borrower, so the mortgage and settlement professionals should confirm the exact requirements.

A different process applies when the household needs the absent service member’s income, credit, assets, VA entitlement, or signature to complete the transaction. The service member may need to participate as a co-borrower, execute specific documents remotely, or authorize another person to act through an approved power of attorney.

The central question is therefore not simply whether the service member is away. It is who will borrow, who will own the property, whose financial qualifications are required, and what authority is needed to sign each document.


Military households beginning a move to the region may find it helpful to review the broader Military Relocation to Hampton Roads: PCS Guide before choosing a financing and closing strategy.

Can the Military Spouse Apply for the Mortgage Alone?

Yes, provided the spouse can qualify under the lender’s requirements.

A spouse applying independently will generally be evaluated using that applicant’s credit, income, employment, debts, assets, and available funds. The service member’s income or military allowances cannot simply be added to the application unless the lender can use them under the applicable loan program and the service member completes any required borrower documentation.

An independent mortgage may be conventional, FHA, USDA, or another available loan product, depending on the borrower, property, location, and lender. The spouse should compare the estimated interest rate, down payment, mortgage insurance, closing costs, reserves, property eligibility, and monthly payment rather than assuming one program is automatically preferable.

Financing in one spouse’s name also does not answer every ownership question. The borrower, lender, settlement provider, and title attorney should determine:

  • Whether both spouses will appear on the deed
  • Whether the non-borrowing spouse must sign any closing documents
  • How title will be held
  • Whether adding a spouse to title affects underwriting or title insurance
  • Whether another signature is required to grant the lender’s lien
  • How the ownership plan affects future sale, refinancing, estate planning, or relocation


The real estate agent should not decide these legal and lending questions. They should be resolved early with the lender and settlement professional so the contract is written around a structure that can actually close.

Can a Military Spouse Use the Service Member’s VA Loan Benefit?

A military spouse generally cannot independently use the service member’s VA entitlement as though it belonged to the spouse. VA home-loan eligibility belongs to the eligible service member, Veteran, or qualifying surviving spouse.

However, a married couple may be able to complete a VA-financed purchase while the service member is away when the eligible service member remains part of the loan and the lender approves the borrower, occupancy, documentation, and signing arrangements.

VA states that its purchase-loan program is available for homes intended for the eligible borrower’s occupancy or, for active-duty service members, the occupancy of a spouse or dependent. VA financing still requires satisfactory credit, sufficient income, and a valid Certificate of Eligibility.

This can be especially important when the service member is deployed, underway, or temporarily assigned elsewhere while the spouse will occupy the home near the household’s duty station.

The lender must evaluate the actual facts. The household should not assume spouse occupancy automatically resolves every question when:

  • The service member has received orders to another location
  • Neither spouse expects to occupy the property soon
  • The property is intended primarily as a rental or investment
  • The service member may separate or retire before closing
  • The couple’s living arrangements are uncertain
  • The anticipated duty station or reporting date has changed
  • A dependent rather than the spouse is expected to occupy the property

VA guarantees loans through private lenders, and the lender must document that the proposed transaction complies with VA requirements and its own underwriting standards.


Buyers preparing a VA-backed offer may also benefit from How First-Time Military Buyers Can Strengthen Their Offer When Using a VA Loan, especially when one spouse will handle most of the transaction locally.

Does the Service Member Have to Be a Co-Borrower?

It depends on the financing structure.

The service member will usually need to be involved as a borrower when the purchase depends on the service member’s VA entitlement or qualifying income. The lender may also need the service member’s credit, debts, employment information, Leave and Earnings Statements, orders, housing allowance, bank records, tax documents, or other underwriting materials.

The service member may not need to be a borrower when the military spouse qualifies independently for a non-VA mortgage. Even then, title and settlement documents may require additional signatures based on how ownership will be structured and what interest the lender needs to secure.

Before touring homes seriously, the couple should ask the lender to explain the proposed structure in writing:

  • Who is applying for the mortgage?
  • Whose income will be used?
  • Whose debts will be considered?
  • Who will appear on the promissory note?
  • Who will sign the deed of trust?
  • Who will appear on the deed?
  • Will the service member need a power of attorney?
  • Can the service member sign remotely instead?
  • What documents will be required from the service member?
  • How will military orders affect occupancy and underwriting?

This planning can prevent the household from discovering after ratification that the intended borrower or title arrangement does not satisfy the lender.

Can the Spouse Use a Power of Attorney for the Home Purchase?

Possibly. A power of attorney can allow one person to sign specified documents for another, but it should never be assumed that an existing general military power of attorney will be sufficient for a mortgage closing.

Virginia law allows a married person to appoint an attorney-in-fact to execute and acknowledge a deed or other writing that the person could execute. The power must be properly prepared, executed, acknowledged, and still in effect.

The lender, settlement company, title insurer, and recording office may have additional requirements. The document may need to identify the property, authorize borrowing, permit execution of the note and deed of trust, address occupancy certifications, authorize amendments, and grant other transaction-specific powers.

For a VA loan using a power of attorney, the lender must also complete the applicable certification confirming that the Veteran is alive and, when on active military duty, not missing in action. VA identifies this as a separate requirement from the power of attorney itself.

A strong process is to have the proposed power of attorney reviewed by the lender and settlement provider before the offer is submitted or immediately after ratification. Waiting until closing week can create serious problems if the document lacks required authority or cannot be recorded.


The household may also want guidance from a military legal-assistance office or qualified private attorney. A real estate professional can coordinate the timeline, but should not draft or interpret legal authority outside the scope of their license.

Is a Power of Attorney Always Necessary?

No. The service member may be able to sign through another approved method.

Depending on the lender, settlement provider, location, and documents involved, available options may include:

  • Secure electronic signing for eligible documents
  • Remote online notarization
  • A mobile notary
  • A mail-away closing package
  • Signing at a military legal office, embassy, consulate, bank, or approved notary location
  • Signing documents earlier than the spouse who is attending settlement
  • A transaction-specific power of attorney

Not every document can necessarily be signed electronically, and not every lender or title insurer accepts every remote process. Time-zone differences, operational security, unreliable internet access, submarine or shipboard communication, field exercises, and classified assignments may make real-time signing difficult.

The couple should establish both a primary and backup closing method. They should also determine whether the service member must be reachable on closing day and what happens if communication is unexpectedly unavailable.


What Happens if You Deploy Before Your Home Purchase Closes? provides a more detailed explanation of deployment-related powers of attorney, lender communication, occupancy, walkthroughs, insurance, and settlement logistics.

How Should the Couple Choose the Right Borrower and Title Structure?

Begin with financing qualification, but do not stop there.

The lender can compare whether the spouse qualifies independently, whether a joint application provides better terms, and whether VA financing is available and suitable. The settlement attorney or title professional can explain the available forms of ownership and the documents required to create the selected title structure.

The couple should also consider:

  • Which spouse will occupy the property initially
  • Whether the household expects another PCS within a few years
  • Whether the service member will return to the home
  • Whose funds are being used for the deposit and closing
  • Whether either spouse owns other real estate
  • Whether the property may later become a rental
  • How future refinancing would work
  • What happens if one spouse must sell while the other remains away
  • Estate-planning and survivorship goals
  • Separation, divorce, or creditor considerations that require legal advice

The mortgage and title decisions are related, but they are not identical. Being named on the deed means having an ownership interest. Being named on the note means being personally obligated to repay the mortgage debt. The lender’s lien documents connect the debt to the property.


The household should obtain advice specific to the transaction rather than relying on a title arrangement used during a previous assignment or recommended casually by someone who is not involved in the current closing.

How Can a Military Spouse Tour Homes While the Service Member Is Away?

The military spouse can tour locally while sharing live video, recordings, photographs, measurements, documents, and observations with the absent service member.

A deliberate virtual-tour process is more useful than simply walking through the home on a video call. Before the showing, the couple should agree on the details that matter most and create a consistent checklist for every property.

The local spouse or agent may examine:

  • Room connections and usable dimensions
  • Natural light at the time of the showing
  • Storage and closet space
  • Visible property condition
  • Exterior maintenance
  • Yard drainage and grading
  • Street access and parking
  • Noise from nearby roads or uses
  • Commute routes selected by the buyer
  • HOA or condominium responsibilities
  • Flood information and insurance considerations
  • Space for household goods arriving later
  • Areas that require specialist inspection

The absent service member should receive the same disclosures, inspection reports, association documents, lender updates, and contract amendments as the spouse who is physically present.


How Virtual Tours Help Military Buyers Relocating From Out of State explains how structured video tours can help buyers compare properties without replacing inspections, disclosures, or independent due diligence.

Who Should Sign the Purchase Agreement?

The correct signers depend on who is buying the property and how the transaction is structured.

A spouse purchasing independently may sign the offer in their own name. When both spouses will be purchasers, both may need to sign, even if one spouse is away. The absent spouse might sign electronically, sign a counterpart, or authorize an attorney-in-fact when the contract and parties permit it.

The names used in the purchase agreement should align with the lender and settlement plan. Adding or removing a purchaser later may require a written amendment and lender approval.

Before submitting an offer, confirm:

  • The legal names of all intended purchasers
  • Whether a trust or other entity is involved
  • Who will provide the earnest-money deposit
  • Which buyer is applying for financing
  • Whether the service member can sign the contract promptly
  • Whether an existing power of attorney covers the offer and amendments
  • How inspection notices and amendments will be approved
  • Who has authority to make decisions if the service member cannot respond


One spouse should not presume they can waive contingencies, approve repairs, increase the purchase price, change financing, or release the earnest-money deposit on behalf of the other without clear authority.

How Can the Couple Protect the Financing Before Closing?

The lender should be told early that the service member will be away.

The lender may need additional time to verify income, military status, occupancy, orders, identity, assets, and signing authority. The service member should respond promptly to document requests whenever operational circumstances permit.

The couple should avoid unexplained transfers between accounts, new credit applications, large purchases, co-signing for other debt, changes in employment, or changes to the expected occupancy plan without first discussing them with the lender.

The spouse handling the transaction locally should also understand that a preapproval is not a final guarantee. Underwriting may continue through closing, and unresolved documentation or a material change can still affect approval.


When financing becomes uncertain, What Happens if the Buyer’s Financing Falls Through Before Closing? explains why the mortgage decision, financing contingency, notice requirements, earnest money, and purchase contract must be evaluated separately.

What Documents Should Be Organized Before Making an Offer?

A military household buying during an absence should organize documents earlier than a household in which both borrowers are locally available.

Depending on the loan and circumstances, the lender or settlement provider may request:

  • Government-issued identification
  • Certificate of Eligibility for VA financing
  • Recent Leave and Earnings Statements
  • Military orders and amendments
  • Civilian income records for the spouse
  • Tax returns and W-2 or 1099 forms
  • Bank and investment statements
  • Documentation of transfers and deposits
  • Gift-fund documentation
  • Current housing and debt information
  • Insurance estimates
  • Marriage documentation when required
  • The proposed power of attorney
  • Lender-specific occupancy certifications
  • Contact information for the service member
  • Confirmation of the approved signing process

Documents can expire during underwriting. The couple should ask which statements, pay records, credit documents, employment verifications, and military records will need to be updated before settlement.

Sensitive documents should be transmitted through secure lender or settlement portals rather than ordinary email whenever possible.

How Should Inspections and Repair Decisions Be Handled?

The spouse who is present can attend the inspection, but both buyers should receive the report and participate in the decision when both are parties to the contract.

The couple should decide before the inspection who has authority to:

  • Request additional specialist evaluations
  • Approve or reject proposed repairs
  • Negotiate credits or price changes
  • Accept the property in its current condition
  • Extend a deadline
  • Terminate under an applicable contingency
  • Approve changes that affect cash needed at closing

A power of attorney may or may not authorize every one of these decisions. Even when the spouse has authority, the couple may want a separate communication plan for major financial or property issues.

The final walkthrough also needs advance planning. The spouse may attend with the agent, but the absent service member should understand what is being verified and how unresolved problems will be handled before signing or funding.

What Happens if the Orders or Occupancy Plan Changes?

Notify the lender and real estate professional immediately.

A change in orders, deployment, expected return date, duty station, separation date, household occupancy, or income may affect underwriting and the suitability of the purchase. It does not automatically end the transaction, but it should not be concealed or left until closing.

The lender may need to determine whether the original financing and occupancy plan remain valid. The parties may also need to evaluate whether the property still fits the household’s practical needs.

The purchase contract determines whether a change in military circumstances gives the buyer a right to delay or terminate. Military orders do not automatically erase every residential purchase obligation. The buyer should have the contract reviewed by an appropriate professional before assuming that deployment, reassignment, or communication difficulty releases the household from the agreement.

How Should Homeowners Insurance and Possession Be Coordinated?

Insurance should be arranged using the actual occupancy and property information.

The insurer may ask who will occupy the home, when occupancy begins, whether the home will be vacant, whether renovations are planned, and whether another person will manage the property while the service member is away.

The lender will generally require acceptable coverage before funding. Flood insurance may also be required or advisable depending on the property and financing.

The household should also establish who will:

  • Receive the keys
  • Transfer utilities
  • Secure the property
  • Meet movers or contractors
  • Address maintenance problems
  • Receive association notices
  • Manage insurance claims
  • Monitor the property if the spouse travels
  • Handle urgent decisions while the service member remains unavailable

Buying the property is only one part of the plan. The household must also be ready to take possession and protect the home after settlement.

What Closing Details Should Be Confirmed in Advance?

Closing, also called settlement, is when the required mortgage and purchase documents are signed. Buyers should know who will sign, where each signer will be, and how documents will travel well before closing day.

The borrower should receive the Closing Disclosure at least three business days before closing for a covered mortgage transaction. Both spouses should review the loan terms, monthly payment, cash to close, credits, interest rate, escrow amounts, and closing costs rather than leaving the review entirely to the spouse who is present.

Confirm:

  • The final signing method
  • Whether originals are required
  • Notarization requirements
  • Time-zone and availability issues
  • The approved power of attorney
  • The VA live-and-well certification, if applicable
  • The final cash-to-close amount
  • Secure wiring instructions
  • Identity-verification procedures
  • Final walkthrough responsibility
  • Possession and key delivery
  • Recording and funding requirements
  • The backup plan if the service member cannot communicate


Wiring instructions should be independently confirmed using a trusted telephone number. A last-minute email changing the destination account should be treated as suspicious until verified directly with the settlement provider.

Frequently asked questions

Can a military spouse buy a house while the service member is deployed?

Yes. A military spouse may purchase independently if they qualify for financing, or the couple may purchase jointly using approved remote signing or a power of attorney. The correct arrangement depends on the mortgage, title structure, whose income and VA eligibility are being used, occupancy, and lender and settlement requirements. The process should be organized before an offer is submitted because the service member’s absence does not remove contract deadlines or document requirements.

Can a military spouse use the service member’s VA loan without them present?

The spouse generally cannot use the service member’s VA entitlement independently. The eligible service member ordinarily remains part of the VA loan, but the spouse may be able to satisfy occupancy for an active-duty borrower and may sign approved documents through a valid power of attorney. The lender must approve the borrower, occupancy, documentation, and closing method. Salyer Wilmoth Homes can help coordinate these questions with a VA-experienced lender and settlement provider before the household commits to a property.

Can a military spouse qualify for a mortgage using only their own income?

Yes. A military spouse may apply using their own income, credit, debts, assets, and employment when they can independently meet the lender’s requirements. The service member may not need to co-sign the mortgage, although title or state-law documents may still require additional signatures. The spouse should obtain lender and settlement guidance before deciding who will appear on the loan and deed.

Can a spouse use a power of attorney to close on a house in Virginia?

Possibly. Virginia recognizes properly executed powers of attorney, but the lender, settlement provider, and title insurer must accept the document and confirm that it grants the authority needed for the specific purchase and mortgage. A general power of attorney may not be sufficient. Salyer Wilmoth Homes can help coordinate early review of the document, while its legal preparation and interpretation should be handled by an appropriate attorney or military legal-assistance office.

Can a military spouse tour and purchase a Coastal Virginia home remotely?

Yes. The couple can use live video tours, document sharing, electronic contract signatures, local inspections, and an approved closing arrangement. Remote tools should supplement—not replace—inspection, title, financing, insurance, flood, association, and property due diligence. Salyer Wilmoth Homes can help create a structured remote-buying plan for Chesapeake, Norfolk, Virginia Beach, Portsmouth, Suffolk, Hampton, Newport News, and nearby Coastal Virginia communities.

This article provides general real estate information and is not legal, lending, tax, title, military-benefits, financial, or settlement advice. Financing, occupancy, signing, and ownership requirements vary according to the borrowers, property, loan program, lender, orders, and jurisdiction. Buyers should consult their lender, settlement provider, title professional, military legal-assistance office, attorney, insurance representative, and other appropriately licensed advisers about their specific circumstances.


Preparing to buy a Coastal Virginia home while your service member is away? Let’s organize the home search, lender communication, virtual tours, contract timeline, inspections, and closing plan before you make an offer.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Posted in Buyer Guides
Aug. 4, 2026

What Happens if the Buyer’s Financing Falls Through Before Closing?

TL;DR


When a buyer’s financing falls through before closing on a Virginia home, the purchase does not automatically disappear, the seller does not automatically receive the earnest-money deposit, and the buyer does not automatically have the right to walk away without consequences, because the outcome depends on the precise financing language in the signed purchase agreement, whether the transaction was expressly contingent on financing, the loan type and approval deadline, whether the buyer applied and cooperated in good faith, why the lender withdrew or denied approval, whether required notice and documentation were delivered on time, and whether the parties can preserve the transaction through an extension, a different lender or loan product, additional verified funds, a price adjustment, an approved seller contribution, or another written amendment; buyers should notify their lender and real estate professional immediately, request a clear written explanation of the unresolved condition, avoid opening new accounts or moving undocumented money, review every contract deadline, and consult appropriate legal or settlement professionals before terminating, while sellers should verify the contractual position, protect the earnest-money process, calculate the cost of waiting against the cost of returning to market, and evaluate any proposed solution using consistent, objective, fair housing-minded standards.

Does a Financing Denial Automatically Cancel the Home Purchase?

No. A lender’s decision to deny, suspend, or withdraw a mortgage does not automatically terminate the purchase agreement.

The lender and the purchase contract serve different functions. The lender decides whether it will fund the buyer’s mortgage under its underwriting requirements. The contract determines what the buyer and seller are obligated to do if financing is delayed or unavailable.

The result may depend on whether the contract is contingent on financing, whether that protection remains active, whether the buyer satisfied the application and cooperation requirements, whether the buyer delivered any required notice by the deadline, and whether the denial falls within the protection stated in the agreement.

Virginia REALTORS® introduced an updated Residential Purchase Contract for use beginning May 4, 2026, with separate provisions addressing transactions in which financing is contingent and transactions in which it is not. However, parties may use other forms or negotiate additional terms, so the actual signed agreement—not a general description of Virginia practice—must control the analysis.


A buyer should therefore avoid saying, “The loan was denied, so the contract is canceled,” until the financing section, amendments, notices, deadlines, and default provisions have been reviewed by the appropriate professionals.

Why Can a Mortgage Fall Through After the Buyer Was Preapproved?

A preapproval is useful, but it is not a guaranteed loan offer. The Consumer Financial Protection Bureau describes preapproval as a lender’s tentative willingness to lend based on assumptions and the information available at that stage.

The lender may continue verifying the borrower, property, insurance, assets, income, debts, and documentation until the transaction is ready to fund. CFPB guidance advises buyers to remain alert for requests for additional documents throughout the closing phase, while lenders may obtain another credit report shortly before closing.

Common reasons financing may become uncertain include:

A change in employment, reduced hours, unpaid leave, or loss of income used to qualify.

A new vehicle loan, credit-card balance, personal loan, co-signed debt, or other obligation that changes the buyer’s debt-to-income calculation.

A late payment, credit-score decline, new collection account, or other credit change.

Large deposits, transfers, gifts, or cash that cannot be documented to the lender’s satisfaction.

A lower-than-expected appraisal or a property condition that does not meet the loan program’s requirements.

An insurance issue that affects the availability, cost, or lender acceptability of coverage.

Incomplete documents, inconsistent information, expired records, or failure to satisfy an underwriting condition.

A change involving occupancy, marital or co-borrower circumstances, immigration documentation, military orders, business income, or another material part of the application.

For many conventional loans governed by Fannie Mae requirements, employment and qualifying income must be documented, and qualifying employment may be verified shortly before closing. Fannie Mae guidance also states that lenders must account for borrower liabilities and respond to credit-related findings.


Buyers who are still preparing to make an offer should understand this distinction before relying too heavily on the letter itself. One Homebuying Step You Don’t Want to Skip: Pre-Approval explains why preapproval matters while reinforcing that it is the beginning of financing preparation rather than the end of underwriting.

What Should the Buyer Do as Soon as Financing Becomes Uncertain?

The buyer should contact the loan officer immediately and request a precise explanation of the problem.

“Your loan may not work” is not enough information to make a contract decision. The buyer needs to know whether the file has been formally denied, conditionally suspended, returned for more documentation, affected by the property, or delayed because an approval condition remains outstanding.

The buyer should ask:

What exact underwriting condition is unresolved?

Has the loan been formally denied, or is additional documentation still being reviewed?

Can the problem be corrected within the existing closing timeline?

Would another loan product, down-payment amount, or financing structure work?

Will the lender provide the documentation required by the purchase agreement?

Does the closing date need to be extended?

What happens to the rate lock if settlement is delayed?

Has the buyer’s updated credit, employment, income, or asset information changed the approval?

At the same time, the buyer should notify the real estate professional so the contract deadlines can be reviewed. The seller should receive only the notices and information required or strategically appropriate under the contract; private financial documents should not be shared casually.


The buyer must also continue responding to legitimate lender requests. A financing contingency may require more than simply obtaining a denial letter. The agreement may impose duties involving timely application, truthful information, reasonable cooperation, payment of lender-related expenses, pursuit of a specified loan, or prompt notice.

Can the Transaction Still Be Saved?

Sometimes. A financing problem shortly before closing is serious, but it is not always permanent.

The available solution depends on the reason for the problem, the time remaining, the buyer’s financial position, the seller’s willingness to cooperate, and the lender’s rules.

The buyer may be able to provide missing documents, explain an account or deposit, pay down an approved debt, document additional income, correct an error, or satisfy another underwriting condition. No debt should be paid, account closed, money transferred, or new obligation created without the lender’s instructions because an attempted solution can create a different underwriting problem.

A different loan product may also be possible. For example, a buyer may qualify under one program but not another, or a revised down payment may produce an acceptable loan-to-value or debt-to-income calculation. This requires new lender figures rather than assumptions.

The parties may agree to extend closing, but an extension should be written and should address any related deadlines. The seller is not automatically required to grant more time, particularly when the financing issue appears unlikely to be resolved.

Switching lenders is another potential path, but it can require the loan process to restart and may place the scheduled closing at risk. CFPB guidance specifically warns that changing lenders can delay or endanger closing.

The parties could also discuss a price adjustment or seller-paid contribution when permitted by the lender and contract. These options may help only when the financing problem relates to cash needed, appraisal value, or approved closing costs. A seller credit cannot cure every income, credit, employment, insurance, or eligibility issue.


When the financing problem began with the property’s value rather than the buyer’s qualification, What Happens if a Virginia Home Appraises Below the Offer Price? explains the separate options involving reconsideration of value, price renegotiation, financing adjustments, appraisal gaps, and contract protections.

Does Receiving a Closing Disclosure Mean the Loan Is Guaranteed?

No. A Closing Disclosure is important, but receiving it should not be treated as proof that the mortgage has funded.

The Closing Disclosure lists the final loan terms, closing costs, and transaction details, and the lender generally must ensure that the buyer receives it at least three business days before consummation. Certain later changes require a corrected disclosure and, in limited circumstances, another three-business-day review period.

However, the closing process may still involve final documents, verification, conditions, signatures, funding, and recording. CFPB’s closing guidance instructs borrowers to continue submitting documents and responding to lender requests through this phase.


Similarly, phrases such as “approved,” “clear to close,” or “closing package ordered” should be understood in the context in which the lender uses them. The buyer should ask whether any conditions remain before funding and whether the lender anticipates another employment, credit, asset, insurance, or property review.

What Happens to the Earnest-Money Deposit?

The earnest-money result depends primarily on the contract and how the financing failure occurred.

If the buyer has an active financing contingency, fulfilled the buyer’s contractual duties, and properly invokes the protection before the applicable deadline, the agreement may provide a basis for termination and return of the deposit.

If the transaction was not contingent on financing, the contingency expired, the buyer failed to apply or cooperate as required, the buyer voluntarily created the disqualifying condition, or the required notice was late or deficient, the seller may argue that the buyer defaulted.

That does not mean the broker may simply choose a winner whenever the parties disagree. Under Virginia law, when a transaction is not completed, a broker holding earnest money generally keeps it in escrow until the parties agree in writing, a court orders disbursement, the funds are interpleaded, or the clear and explicit contract terms authorize release through the statutory process.


A buyer or seller should not sign a release merely because the other party says it is routine. A release may determine who receives the deposit and may also waive additional claims. Disputed situations should be reviewed by a qualified Virginia real estate attorney.

Can the Seller Keep the Buyer’s Earnest Money After a Loan Denial?

Possibly, but not automatically.

The seller’s position may be stronger when the buyer agreed to purchase without a financing contingency, waived the applicable protection, missed a deadline, failed to pursue the agreed loan, provided inaccurate information, made a disqualifying financial change, or otherwise breached the contract.

The buyer’s position may be stronger when financing was a valid contingency, the buyer applied promptly and acted in good faith, the lender denied the loan for a covered reason, and all required notices and documentation were delivered correctly and on time.

The seller should avoid relisting, signing another contract, authorizing deposit disbursement, or declaring default without reviewing the termination provisions and obtaining appropriate advice. The practical desire to move on quickly should not replace the written process.

What Options Does the Seller Have if Financing Fails?

The seller generally has to decide whether preserving the transaction is more valuable than returning the property to the market.

An extension may make sense when the financing issue is narrow, documented, and likely to be corrected within a reasonable period. Before agreeing, the seller may ask for an updated lender explanation, revised approval timeline, proof of additional funds where appropriate, or another term that improves certainty.

The seller may also consider a price adjustment or permitted closing-cost contribution, but only after reviewing the estimated net proceeds and confirming that the lender can use the proposed concession. A concession that does not solve the lender’s actual condition merely reduces the seller’s proceeds without saving the transaction.

When the problem appears unlikely to be resolved, the seller may prefer a contract termination and prompt return to market. That decision should account for carrying costs, market timing, showing disruption, the property’s prior days on market, disclosure obligations, the availability of backup interest, and the risk that the next buyer encounters the same property-related financing issue.

A failed transaction may also affect how future buyers interpret the listing. The seller and listing agent should accurately explain the status without disclosing confidential borrower information or implying that the property itself caused the failure unless that is supported by the facts.

Should the Buyer Use Additional Cash to Preserve the Purchase?

Only after the lender confirms that additional funds would solve the problem and verifies that the source is acceptable.

A buyer might be able to increase the down payment, cover a limited appraisal gap, pay an approved obligation, or bring more money to closing. However, buyers should not assume every financing denial is simply a cash shortage.

More cash will not necessarily cure insufficient qualifying income, unstable employment, unacceptable credit, unresolved property eligibility, inadequate insurance, missing documentation, or another underwriting condition.

The buyer should also consider financial stability after closing. Saving the transaction by using nearly every available dollar may create a different problem once moving costs, repairs, utilities, insurance deductibles, and ordinary ownership expenses begin.

How Much Cash Should First-Time Buyers Keep After Closing? offers a useful framework for deciding whether an increased cash contribution would leave the buyer financially prepared or merely able to reach the closing table.


Buyers should also compare the revised loan figures with the complete ownership budget. Extra Costs That Can Surprise Buyers Near Coastal Virginia explains how insurance, escrow funding, association dues, moving costs, maintenance, and coastal property considerations can change affordability beyond the advertised mortgage payment.

How Buyers Can Reduce the Risk of a Last-Minute Loan Problem

Buyers should treat financial consistency as part of the homebuying process until the loan has funded and closing is complete.

Avoid applying for new credit, co-signing for another person, financing furniture or a vehicle, increasing revolving balances, moving large amounts of money without documentation, changing jobs without speaking to the lender, or making major purchases from accounts intended for closing.

Respond quickly to lender requests and keep copies of submitted records. Ask whether documents are nearing expiration and whether updated pay statements, bank statements, insurance records, tax documents, military records, or business-income information will be required.

Review the Loan Estimate and Closing Disclosure carefully. Ask questions when the payment, cash to close, interest rate, loan product, credits, escrows, or other terms differ from earlier expectations. CFPB guidance states that a borrower does not have to sign closing documents when the loan terms are not satisfactory and should obtain an explanation for material changes.


Military buyers should promptly report changes involving orders, duty station, deployment, housing allowance, expected occupancy, or access to closing documents. What Happens if You Deploy Before Your Home Purchase Closes? explains how deployment can affect underwriting verification, occupancy, powers of attorney, remote signing, walkthroughs, and funding logistics.

How Sellers Can Reduce Financing Risk Before Accepting an Offer

A preapproval letter remains useful, but the seller should evaluate the entire offer rather than relying on one document.

Relevant terms may include the loan type, down payment, financing contingency, appraisal protection, requested concessions, deposit, proposed closing date, prior property-sale contingency, and the lender’s ability to meet the schedule.

The seller’s agent may seek permitted clarification regarding whether the lender reviewed income, assets, credit, and required documentation, but should not request or circulate confidential financial records unnecessarily.

A stronger offer is not always the one with the highest price. A slightly lower offer with realistic financing, adequate cash, manageable contingencies, and a credible closing plan may produce a better practical result than an offer whose price depends on assumptions the lender has not reviewed.


Sellers should still avoid demanding guarantees that no lender can honestly provide. Even a carefully underwritten buyer can experience an unexpected employment change, fraud alert, property issue, insurance problem, appraisal shortage, or another material event before closing.

Financing Problems for VA, FHA, and Other Loan Programs

Different mortgage programs have different underwriting, property, appraisal, insurance, and documentation requirements.

A VA buyer may have strong eligibility and still need to satisfy the lender’s credit, income, residual-income, occupancy, appraisal, property, and documentation requirements. The VA escape clause is specifically tied to the VA-established reasonable value and is not a general right to cancel for any unrelated financing problem.

An FHA transaction may include specific appraisal-related language, but that language should not be confused with a general mortgage approval guarantee. HUD’s model amendatory clause addresses the appraised valuation and preserves the buyer’s option to proceed despite that valuation; it does not replace the private contract’s broader financing terms.


Conventional, USDA, jumbo, portfolio, down-payment-assistance, and other financing may each involve different conditions. Buyers and sellers should avoid assuming that one program’s rule applies to another.

Why Contract Deadlines Matter

Financing problems are often made worse by delay.

A purchase agreement may establish deadlines for loan application, lender documentation, financing approval, appraisal review, notice of denial, removal of contingency, settlement, or termination. A buyer who had a legitimate financing problem may weaken the contractual position by failing to communicate or provide notice on time.

A seller who informally agrees to “give the buyer a few more days” may also create uncertainty when the extension is not documented.


Written amendments should address the new closing date and any connected deadlines rather than changing one date while leaving the remaining contract ambiguous. Verbal assurances from the buyer, seller, agent, or loan officer should not be treated as substitutes for the notices and signatures required by the agreement.

Keeping the Financing Conversation Fair Housing-Minded

Financing discussions should remain focused on objective transaction terms and documented ability to perform—not assumptions about buyers based on identity, household composition, military service, disability, national origin, age, or another protected characteristic.

Virginia’s Fair Housing Law applies to residential sales, mortgage financing, insurance, brokerage, and advertising. Protected classes include race, color, religion, national origin, sex, elderliness, familial status, disability, source of funds, sexual orientation, gender identity, and military status. The law also prohibits applying different standards because someone belongs to a protected class.

The parties may evaluate legitimate contract terms such as price, deposit, contingency language, closing date, requested contributions, and documented ability to complete the transaction. However, they should avoid discriminatory statements, inconsistent requirements, blanket assumptions about who is financially reliable, or language implying that a home is available only to a preferred type of buyer.


Questions about whether a particular financing policy or offer-evaluation practice complies with Virginia fair housing requirements should be directed to qualified legal counsel.

Frequently asked questions

What happens if a buyer’s mortgage is denied before closing?

The buyer and seller must review the financing provisions, notice requirements, deadlines, and default terms in their signed purchase agreement. The parties may extend closing, revise approved financial terms, allow the buyer to pursue another loan, or terminate when the contract permits. A mortgage denial does not by itself decide whether the contract ends or who receives the earnest-money deposit.

Can a buyer get the earnest-money deposit back if financing falls through?

Possibly. A buyer may be entitled to the deposit when a valid financing contingency applies and the buyer satisfied the agreement’s application, cooperation, documentation, and notice requirements. If the protection expired or the buyer defaulted, the seller may dispute the return. Salyer Wilmoth Homes can help organize the relevant dates and transaction documents so the parties can raise the right questions with the settlement provider or a Virginia real estate attorney.

Can a mortgage be denied after the buyer is cleared to close?

Yes. A lender may still discover a material change or unresolved condition involving employment, income, credit, debts, assets, insurance, occupancy, fraud prevention, or the property before funding. Buyers should continue responding to the lender and avoid major financial changes until the loan has funded and settlement is complete.

Can the buyer switch lenders before closing?

The buyer may be able to change lenders, but the new lender may need to repeat underwriting, disclosures, appraisal review, title coordination, and other parts of the process. That can require an extension and does not guarantee approval. Salyer Wilmoth Homes can help coordinate the proposed timeline with the seller, lender, and settlement company before the parties decide whether an extension is realistic.

What should a seller do when the buyer’s financing falls through?

The seller should confirm whether the financing issue is temporary or final, review the contract and earnest-money provisions, request appropriate documentation through the proper channels, and compare a possible extension or amendment with the cost of returning to market. Salyer Wilmoth Homes can help sellers evaluate the transaction’s practical options while keeping confidential borrower information, contract deadlines, and fair housing responsibilities in mind.

This article provides general real estate information and is not legal, lending, financial, tax, underwriting, or settlement advice. Contract rights and mortgage requirements vary by transaction. Buyers and sellers should consult their lender, settlement provider, attorney, tax professional, and other appropriately licensed advisers regarding their specific circumstances.


Concerned that financing may interrupt a Coastal Virginia home purchase? Let’s review the timeline, contract terms, lender status, and practical options before the next deadline arrives.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Aug. 4, 2026

Standing Water After Rain: When Is Yard Drainage a Serious Concern?

TL;DR

Standing water after an unusually heavy Coastal Virginia rain does not automatically mean a property has a major defect, but recurring puddles, water that remains long after nearby areas have dried, runoff flowing toward the foundation, saturated soil beside a crawl space, erosion, damaged landscaping, overflowing drainage structures, or moisture appearing inside the home can point to grading, soil, downspout, stormwater, groundwater, or drainage-system problems that deserve closer investigation; buyers should observe the property during or shortly after rain, review the yard’s slope, gutters, downspouts, crawl space, foundation, low areas, drains, swales, neighboring runoff, flood information, permits, disclosures, insurance considerations, and inspection findings before assuming the issue is minor, while sellers should document known conditions, correct simple maintenance problems where appropriate, avoid cosmetic attempts to conceal wet areas, and consult qualified drainage, landscaping, structural, crawl-space, or engineering professionals when the source, severity, repair method, or effect on the home remains uncertain.

Is Standing Water After Rain Always a Serious Problem?

Not necessarily. Soil needs time to absorb water, and a very intense or prolonged storm can temporarily overwhelm even a generally functional yard. Low areas may hold shallow puddles for a short period, especially when the ground was already saturated before the rain began.

The important questions are how frequently the water appears, how long it remains, where it collects, and whether it affects the house or surrounding improvements.

A small puddle in a distant part of the yard after an exceptional storm is different from water repeatedly collecting beside the foundation after ordinary rainfall. A low spot that dries later the same day is also different from a saturated area that remains soft, muddy, or covered with water for several days.


Well-designed rain gardens, which are intentionally constructed to hold and absorb runoff, are generally expected to drain within approximately 24 to 48 hours after a storm. An ordinary yard is not automatically subject to the same design standard, but that time frame can serve as a useful screening reference: water that remains beyond it, appears after moderate rain, or repeatedly affects the same location deserves closer evaluation.

How Long Is Too Long for Water to Stand in a Yard?

There is no single deadline that applies to every property because drainage depends on rainfall intensity, soil type, slope, groundwater, vegetation, temperature, previous saturation, and the amount of hard surface directing runoff into the yard.

As a practical starting point, buyers and homeowners should pay closer attention when visible water remains for more than 24 to 48 hours, especially when surrounding areas have already dried. Water that remains for several days may indicate slow infiltration, compacted soil, heavy clay, a blocked outlet, improper grading, a high seasonal water table, or more runoff entering the area than the yard can manage.

Virginia Cooperative Extension notes that standing water may indicate a wet site or slow drainage, while compacted soil can restrict the movement of water into the ground. Compaction reduces the larger pore spaces that normally help water infiltrate and drain.

The location matters as much as the duration. Even temporary water deserves attention when it reaches the foundation, crawl-space vents, exterior doors, garage, HVAC equipment, septic components, retaining walls, or neighboring property.

What Causes Standing Water After Rain?

Standing water is a symptom rather than a diagnosis. Several conditions may contribute to the same visible puddle.

The yard may contain a naturally low area where water collects. The soil may have been compacted by construction equipment, vehicles, repeated foot traffic, or previous landscaping work. Heavy or poorly draining soil may absorb water slowly. The lot may also have inadequate slope, or the ground may have settled over time and begun directing water toward the house.

Roof runoff is another common factor. Clogged gutters, disconnected downspouts, damaged underground drain lines, or downspouts that terminate too close to the structure can concentrate a large amount of water in one location.

Hard surfaces also change how water moves. Roofs, patios, driveways, walkways, pools, sheds, and additions prevent rainfall from soaking directly into the ground. If the property was altered without a corresponding drainage plan, more runoff may now reach the lawn or adjoining properties.

Runoff may also enter from neighboring lots, streets, alleys, common areas, drainage easements, ditches, or stormwater facilities. EPA guidance explains that grading, vegetation, soil conditions, and impervious surfaces all affect whether stormwater infiltrates, moves across the land, or becomes concentrated in a particular area.

When Does Yard Drainage Become a Serious Concern?

Standing water deserves prompt professional attention when it appears to be affecting the structure, creating erosion, damaging improvements, or becoming more frequent.

Water repeatedly collecting against the foundation is a stronger warning sign than a shallow puddle at the far edge of the property. Buyers should also investigate moisture or staining inside the crawl space, basement, garage, or lower-level rooms; musty odors; deteriorated wood; rusted components; efflorescence on masonry; damaged insulation; standing water beneath the home; or sump equipment that appears to operate continuously.

Other concerns may include soil washing away from the foundation, channels forming through the lawn, exposed roots, shifting pavers, cracked or leaning retaining walls, sinking areas, damaged fencing, soft ground around patios or decks, and water crossing a driveway or entrance route.

Repeated saturation can also affect lawns, shrubs, and trees because excess water fills soil air spaces and reduces the oxygen available to roots. Virginia Cooperative Extension explains that prolonged low-oxygen soil conditions can interrupt water and nutrient uptake and contribute to plant decline.


A visually attractive yard can still require expensive or ongoing drainage work. Buyers who want to evaluate appearance alongside future upkeep may find How to Spot a Home That Is Beautiful but High-Maintenance helpful, particularly when the property includes mature trees, retaining walls, extensive landscaping, irrigation, patios, drainage structures, or a crawl space.

Why Water Near the Foundation Requires More Attention

The ground immediately around a home should be evaluated carefully because water concentrated near the structure can interact with the foundation, crawl space, basement, slab edges, exterior materials, and mechanical systems.

A drainage concern does not automatically mean structural damage has occurred. However, repeated saturation near the foundation can create conditions that warrant a more detailed inspection, especially when water appears beneath the home or when the buyer observes movement, cracking, wood deterioration, moisture, mold-like growth, or persistent odors.

Gutters and downspouts should also be reviewed as part of the same system. A roof collects a substantial volume of water during a storm, and a blocked or poorly directed downspout may release that water beside the house rather than moving it to an appropriate discharge location.


Buyers should determine whether downspouts discharge onto splash blocks, extensions, underground pipes, rain barrels, landscaped areas, or another approved drainage feature. Underground drainage should not be assumed to function merely because a pipe disappears beneath the soil. Ask where it terminates and whether it has been inspected, cleaned, repaired, or replaced.

What Buyers Should Look for During a Showing

A dry-weather showing can conceal how a property behaves during rain. Buyers should therefore look for indirect evidence even when no water is visible.

Possible clues include bare or thin grass in low areas, moss, algae, mud lines, washed mulch, displaced gravel, eroded channels, water stains on fences or foundation walls, sediment around drains, unusually soft ground, multiple sump-pump discharge lines, recently added soil, new sod in one isolated section, or downspout extensions that appear temporary.

Check whether the yard slopes toward or away from the home. Observe whether nearby patios, driveways, walkways, and neighboring properties direct water toward the lot. Look into visible drains, swales, ditches, culverts, and catch basins for debris or signs of overflow.

The best opportunity may be a showing scheduled during or shortly after rainfall. Virginia Cooperative Extension recommends observing a landscape during or shortly after rain to see where runoff from roofs, driveways, patios, and other hard surfaces actually travels.


Buyers evaluating a Coastal Virginia property should not stop with the yard. They should also inspect the crawl space, foundation areas, garage, lower rooms, HVAC location, gutters, roof drainage, and accessible exterior walls. When the home sits near tidal water, a creek, canal, marsh, pond, or other water feature, What Buyers Should Know About Buying Near the Water in Deep Creek offers a broader framework for reviewing drainage, moisture, flood information, shoreline conditions, maintenance, permits, and insurance.

 Does a Flood Zone Tell You Whether the Yard Drains Properly?

No. A FEMA flood-zone designation and a property’s everyday yard drainage are related topics, but they are not the same question.

Flood maps help describe mapped flood hazards. They do not show whether a particular downspout is clogged, whether a backyard low spot holds water after thunderstorms, whether an underground drain is broken, or whether recent landscaping changed the direction of runoff.

A property outside a higher-risk mapped flood zone may still experience standing water from rainfall, grading, soil conditions, storm-drain backup, or nearby runoff. Likewise, a property inside a mapped flood area may have well-maintained lot drainage but still face broader flood and insurance considerations.

An elevation certificate also does not substitute for drainage analysis. It may report surveyed elevations around the structure, but it does not normally determine whether the backyard ponds after rain, whether gutters work properly, or whether a ditch, culvert, or storm drain performs adequately. What an Elevation Certificate Tells a Coastal Virginia Buyer explains how buyers can use the document without mistaking it for a drainage study.

Buyers should evaluate both issues separately and then consider how they interact.

Could Standing Water Affect Insurance or Financing?

A puddle in the yard does not automatically create an insurance or financing problem. However, related conditions may influence a buyer’s decision, an insurer’s evaluation, required repairs, or the cost and availability of coverage.

For example, visible water intrusion, unresolved foundation concerns, damaged drainage systems, recurring crawl-space moisture, or a property’s mapped flood designation may lead to additional questions. The result depends on the specific property, insurance carrier, lender, loan program, inspection findings, and repair history.

A standard homeowners policy and a separate flood policy cover different risks, and neither should be assumed to pay for every form of water damage. Buyers should explain the property’s condition accurately to the insurance representative and ask what is covered, excluded, or subject to a deductible.


What Buyers Should Know About Flood Insurance Before Buying Near Norfolk or Chesapeake can help buyers connect flood-zone research with drainage observations, elevation information, lender requirements, and total monthly ownership cost.

What Should Sellers Do About Standing Water Before Listing?

Sellers should begin by observing the property during actual rain rather than guessing about the source from dry conditions.

Simple maintenance may resolve some concerns. Gutters may need cleaning, a downspout extension may have become disconnected, a drain may be covered with leaves, or a swale may be obstructed by accumulated soil or landscaping materials.

Other situations require professional evaluation. Regrading, installing underground drains, changing discharge locations, constructing swales, modifying retaining walls, connecting to stormwater infrastructure, or altering areas near easements and property lines can create technical, legal, permitting, and neighbor-related issues when performed incorrectly.

Sellers should avoid covering a wet area with new mulch, sod, gravel, or soil merely to improve photographs or hide the condition. Added material may conceal the symptom without correcting the direction or volume of water.

Virginia’s residential disclosure system also places significant responsibility on buyers to investigate the property, but sellers should not make false statements, actively conceal known defects, or assume that a disclaimer eliminates every obligation. Virginia’s 2026 Residential Property Disclosure Statement: What Coastal Virginia Buyers and Sellers Need to Know provides a broader explanation of why buyers should conduct independent due diligence and why sellers should answer direct questions carefully.


Before listing, organize any available invoices, warranties, permits, surveys, drainage plans, engineering reports, waterproofing documents, foundation records, crawl-space service reports, flood documentation, and photographs showing completed work.

Which Drainage Solutions May Be Considered?

The correct solution depends on the cause. Installing a French drain because water is visible may not solve a grading issue, and adding soil may redirect runoff toward the house or a neighboring property.

Possible approaches may include correcting gutter and downspout problems, cleaning or repairing underground drain lines, restoring a swale, relieving soil compaction, improving vegetation, modifying the grade, installing a catch basin or channel drain, creating a properly designed rain garden, using permeable materials, addressing retaining-wall drainage, or installing specialized foundation or crawl-space systems.

A rain garden is a planted shallow depression intentionally designed to hold runoff temporarily while water infiltrates, evaporates, or is used by vegetation. Virginia Cooperative Extension recommends evaluating the site and conducting a percolation test before selecting a location because every landscape, soil profile, and runoff pattern is different.

Drainage work should also account for buried utilities, septic systems, wells, easements, rights-of-way, property boundaries, local requirements, and the seasonal water table. Larger swales and more complex grading projects may require a contractor, engineer, landscape professional, or other qualified specialist.


The goal is not simply to move water out of one visible puddle. It is to manage runoff without damaging the house, neighboring land, public infrastructure, or another part of the same property.

Who Should Evaluate a Yard Drainage Problem?

The appropriate professional depends on the symptoms.

A licensed home inspector may identify visible drainage concerns and recommend further evaluation. A drainage or grading contractor may assess surface-water movement and possible correction methods. A landscape professional may evaluate soil, vegetation, swales, and rain-garden options.

A structural engineer may be appropriate when settlement, foundation movement, retaining-wall concerns, or structural damage is suspected. A crawl-space or waterproofing specialist may evaluate water beneath the home, although buyers should compare recommendations carefully when the evaluator also sells a specific repair system.

A licensed surveyor or civil engineer may be needed when elevations, lot grading, easements, drainage plans, or runoff between properties are central to the issue. Local stormwater or public-works staff may be able to clarify responsibility for public ditches, inlets, culverts, or drainage easements, but they may not repair conditions located entirely on private property.


Buyers should ask each professional to identify the suspected source, explain the proposed correction, describe what the work will and will not solve, identify permits or approvals that may be necessary, and provide a written estimate whenever possible.

How Buyers Can Protect Their Decision Before Closing

Begin with the purchase agreement and inspection deadlines. A buyer should not wait until the final walkthrough to investigate a drainage concern first observed during the home inspection.

Request available drainage documentation, seller disclosures, repair invoices, permits, surveys, flood information, elevation certificates, insurance records where appropriate, and reports from previous contractors. Ask whether standing water occurs only after exceptional storms or after routine rainfall, how long it typically lasts, and whether water has entered the home, crawl space, garage, or other structures.

Return to the property after rain when access and contract timing permit. Photograph the condition and note the approximate rainfall, time, location, depth, and duration. Those observations can help a professional distinguish between temporary saturation and recurring drainage failure.


Obtain estimates before assuming the repair will be minor. Even when a practical correction exists, buyers should consider the cost, disruption, maintenance, warranty, effect on landscaping, effect on neighboring properties, and possibility that more than one condition contributes to the problem.

Frequently asked questions

How long should water stand in a yard after rain?

Some temporary pooling can occur during heavy or prolonged rainfall, especially when the soil was already saturated. As a practical screening benchmark, water that remains for more than approximately 24 to 48 hours, repeatedly appears after moderate rain, or stays after nearby areas have dried should be evaluated more closely. Soil type, grading, rainfall intensity, groundwater, vegetation, and drainage systems all influence how quickly an individual yard should dry.

Is standing water near the foundation always a serious problem?

It does not automatically prove that the foundation is damaged, but repeated water beside the structure deserves prompt attention. Buyers should look for crawl-space moisture, staining, odors, wood deterioration, foundation movement, damaged insulation, clogged gutters, short downspouts, and soil sloping toward the home. Salyer Wilmoth Homes can help buyers organize the inspection questions and specialist evaluations that should be completed before important contract deadlines expire.

Can a home inspection identify yard drainage problems?

A home inspector can document visible grading, drainage, gutter, downspout, foundation, and moisture concerns, but a standard inspection may not determine the complete cause or design the final repair. Drainage conditions can also be difficult to evaluate when the property has been dry for an extended period. When concerns remain, Salyer Wilmoth Homes can help coordinate follow-up questions for a drainage contractor, engineer, surveyor, crawl-space specialist, or other appropriate professional.

Does being outside a flood zone mean the yard has good drainage?

No. Flood-zone mapping and lot drainage address different issues. A property outside a higher-risk mapped flood area may still have standing water caused by poor grading, compacted soil, blocked drains, roof runoff, groundwater, stormwater backup, or runoff from nearby land. Buyers should review the flood designation and the property’s actual drainage performance separately.

Who should fix standing water in a yard?

The right professional depends on the source. A gutter contractor may address roof discharge, while a grading or drainage contractor may evaluate surface water. A landscape professional may assess soil, vegetation, swales, or rain-garden options. A surveyor, civil engineer, structural engineer, crawl-space specialist, or local stormwater office may be appropriate for more complex conditions. Salyer Wilmoth Homes can help buyers and sellers identify which questions need answers before comparing repair proposals.

This article provides general real estate information and is not engineering, structural, landscaping, insurance, legal, environmental, or drainage advice. Conditions and requirements vary by property and jurisdiction. Buyers and sellers should consult appropriately licensed professionals about the specific home and proposed work.


Concerned about standing water around a Coastal Virginia property? Let’s review what is visible, what documents are available, which questions should be raised, and which professionals may need to evaluate the condition before you make your next decision.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Posted in Buyer Guides
Aug. 4, 2026

Ghent or Olde Towne Portsmouth: Comparing Two Historic Urban Communities

TL;DR

Ghent in Norfolk and Olde Towne Portsmouth both offer historic architecture, urban convenience, established streets, access to restaurants and cultural destinations, and a homebuying experience that feels different from a newer suburban community, but the better fit depends on the specific property and the buyer’s priorities because Ghent may provide a more continuous connection to Norfolk’s medical, cultural, dining, and downtown corridors while Olde Towne may appeal to buyers who value Portsmouth’s historic waterfront setting, High Street access, ferry connections to Norfolk, and a concentrated collection of period homes; before choosing between them, buyers should compare property type, renovation history, exterior-review requirements, parking, flood exposure, insurance, commute routes, public transportation, noise, storage, association obligations, accessibility, maintenance expectations, and total monthly cost rather than relying only on charm, reputation, or a short visit.

Why Buyers Compare Ghent and Olde Towne Portsmouth

Ghent and Olde Towne Portsmouth often attract buyers who want more than a conventional subdivision or recently built house. Both communities offer architectural character, proximity to established commercial and cultural areas, and a more urban daily rhythm than many suburban parts of Coastal Virginia.

The comparison is not as simple as deciding which community is more historic. Ghent’s locally designated historic district includes the Ghent and North Ghent National Register districts, which the City of Norfolk describes as planned neighborhoods built around the turn of the 20th century and influenced by City Beautiful and Beaux Arts planning. Olde Towne Portsmouth developed around one of the region’s historic seaports and is known for a substantial collection of period homes near the Elizabeth River waterfront.

The stronger question is how each location supports the way a buyer expects to live. Someone may prioritize walking to restaurants, medical facilities, cultural venues, or daily services. Another buyer may place greater value on waterfront access, ferry service, a particular historic-home style, or routes toward Portsmouth, Suffolk, Chesapeake, or Norfolk.

Neither community is universally better. The decision should come from comparing the exact home, ownership responsibilities, location, route, and financial picture.

How the Overall Setting Feels Different

Ghent is part of Norfolk’s larger urban network. Its residential streets connect with commercial corridors such as Colley Avenue and 21st Street, while Downtown Norfolk, medical facilities, museums, entertainment venues, and other city destinations are positioned nearby. The result can feel active and interconnected, although the experience changes depending on whether a property is near a commercial corridor, a busier road, a quieter residential block, or the edge of the district.

Olde Towne Portsmouth has its own compact urban identity centered around historic streets, High Street, the waterfront, civic buildings, museums, restaurants, and the Portsmouth side of the Elizabeth River. Some locations may feel closely connected to downtown activity, while others may feel more residential despite being only a few blocks away.

Buyers should avoid making a decision after one weekend visit. A property can feel different during weekday commuting hours, evening dining activity, scheduled events, ferry operations, deliveries, and ordinary residential routines. The questions in Norfolk Homebuying Beyond the Listing: Noise, Access, and Daily Flow are especially useful here because sound, parking, traffic movement, entry routes, and surrounding activity can matter as much as the home’s interior.

Comparing Historic Architecture and Available Home Types

Ghent may include historic detached houses, attached residences, townhomes, condominiums, converted buildings, and properties that have been renovated to different degrees. Buyers may encounter tall ceilings, hardwood floors, decorative trim, front porches, traditional room arrangements, masonry exteriors, or other details associated with older construction.

Olde Towne also offers historic architecture, but its visual character is closely tied to Portsmouth’s development as a port city. Depending on available inventory, buyers may find period houses, attached homes, renovated residences, condominiums, and properties with compact lots or urban-style outdoor space. The City of Portsmouth describes Olde Towne as having one of the largest collections of period homes in the corridor between Charleston and Alexandria.

Architectural appeal should not replace due diligence. Two homes that appear equally charming from the street can have very different renovation histories, system ages, structural conditions, parking arrangements, storage, flood considerations, and future repair budgets.

Buyers attracted to either location should read What Buyers Should Know About Older Homes in Norfolk Before Making an Offer. Although the article focuses on Norfolk, its questions about roofing, plumbing, electrical systems, crawl spaces, moisture, foundation conditions, permits, windows, HVAC equipment, and renovation quality are equally valuable when evaluating an older Portsmouth property.

Which Community Offers the More Connected Daily Routine?

Ghent may work well for buyers whose routines revolve around Norfolk. Depending on the property, restaurants, coffee shops, retail businesses, medical facilities, cultural destinations, and downtown employment areas may be accessible through a combination of walking, biking, transit, or a short drive.

That convenience can come with tradeoffs. Some properties may have limited private parking, smaller outdoor areas, nearby commercial activity, older building systems, association fees, or more street movement than a buyer expects. Distance on a map also does not guarantee that a particular destination will be comfortable to reach on foot from every Ghent address.

Olde Towne may offer a compact routine built around High Street, the waterfront, downtown Portsmouth destinations, and connections across the Elizabeth River. Hampton Roads Transit operates ferry service between Portsmouth and Norfolk, with stops serving the Portsmouth waterfront and Waterside in Norfolk. Service schedules can change by season and operating conditions, so buyers who expect to use the ferry regularly should test the trip and verify the current schedule rather than treating it as an abstract neighborhood amenity.

A useful comparison is to list the places you visit during a normal week and test them from actual properties in both communities. Compare the route to work, grocery stores, medical appointments, military installations, recreation, frequently visited businesses, and other destinations that matter to you.

Parking, Garages, and Outdoor Space Can Change the Decision

Parking deserves attention early in either search.

A Ghent property may offer a driveway, garage, assigned condominium space, shared parking arrangement, or street parking. Buyers should verify what legally conveys with the property, whether parking is deeded or assigned, whether permits apply, and how the street functions during evenings and weekends.

Olde Towne properties can also vary widely. Some may have private parking or rear access, while others may depend more heavily on on-street arrangements. Narrow lots, historic streetscapes, alleys, adjoining structures, and compact outdoor areas may influence how residents handle vehicles, deliveries, trash collection, guests, bicycles, and property maintenance.

During a showing, buyers should ask where each vehicle would go, whether the garage can accommodate a modern vehicle, how groceries would be unloaded, where guests would park, and whether outdoor space provides the privacy or usability they expect.

A beautiful historic façade will not compensate for a parking arrangement that creates frustration every day. The best property is the one whose practical details support the buyer’s routine after the excitement of the showing fades.

How Commutes From Ghent and Olde Towne Differ

Ghent may provide practical access to Downtown Norfolk, Sentara Norfolk General Hospital, Eastern Virginia Medical School, Old Dominion University, Naval Station Norfolk, and other Norfolk destinations, depending on the address and route. However, traffic timing, railroad crossings, events, construction, gate access, and the buyer’s work schedule can alter the actual trip.

Olde Towne may be useful for buyers traveling within Portsmouth or toward Norfolk, Chesapeake, Suffolk, shipyard-related employment, regional highways, or other Hampton Roads destinations. Reaching certain Norfolk locations may involve the ferry, a tunnel, a bridge, transit, or a combination of routes.

Buyers connected to a military installation should not compare the two communities using mileage alone. Naval Station Norfolk Commute Reality: How It Can Shape Your Home Search explains why route reliability, gate choice, work hours, tunnels, traffic patterns, and backup options may be more informative than the estimated drive time displayed during a quiet part of the day.

Drive the expected route from a specific property during realistic travel hours. Then test an alternative route. A home that appears farther away may produce a more manageable routine, while a geographically closer property may include delays that are not obvious from the listing.

Historic-District Rules Should Be Reviewed Before Buying

Historic-district designation helps preserve architectural character, but it can also affect what an owner may change on the exterior of a property.

Norfolk’s Architectural Review Board reviews exterior alterations, new construction, and some demolition within the city’s local historic districts. Approved work may require a Certificate of Appropriateness. The relevance of those rules depends on the property, the proposed project, and the boundaries of the applicable district.

Portsmouth also maintains historic-district design guidelines and a Historic Preservation Commission that reviews qualifying alterations to historic structures in districts including Olde Towne. Buyers planning to replace windows, modify porches, change exterior materials, construct additions, alter fences, or complete other visible work should consult the city before assuming a project will be approved.

Historic oversight is not automatically a disadvantage. It can help protect the visual character that attracted the buyer in the first place. However, it may affect project timing, material choices, contractor requirements, approval procedures, and renovation costs.

Before closing, buyers should determine whether the individual property is within a local historic district, which features are subject to review, whether previous work was approved, and whether their future plans appear compatible with applicable guidelines.

Flood Exposure, Insurance, and Coastal Maintenance Matter in Both Areas

Both communities are part of Coastal Virginia, and proximity to tidal water means buyers should evaluate flood and drainage information at the property level.

Olde Towne’s waterfront setting makes water proximity a visible part of the community, but flood exposure is not determined solely by whether a home has a water view. Ghent properties may also have property-specific drainage, elevation, flood-zone, or insurance considerations.

Buyers should review current flood maps, obtain insurance estimates, ask whether an elevation certificate exists, inspect crawl spaces and lower levels, evaluate lot drainage, and investigate available information about prior water intrusion. They should also consider how moisture, humidity, wind, and coastal weather may affect masonry, woodwork, roofing, windows, HVAC equipment, exterior paint, and metal components.

Waterfront Proximity Near Norfolk or Virginia Beach: A Buyer’s Guide to Risk, Cost, and Lifestyle provides a useful framework for comparing the appeal of a coastal setting with insurance, elevation, drainage, upkeep, access, and resale considerations.

A historic home near the water can be an excellent purchase when its condition, documentation, insurance costs, and maintenance responsibilities are understood. The goal is not to avoid coastal properties; it is to know what the setting may require.

Comparing Condominiums, Attached Homes, and Detached Houses

Property type may ultimately matter more than the community name.

A Ghent condominium may offer access to an urban Norfolk routine with less individual exterior maintenance, but the buyer may need to review association dues, reserves, insurance structure, parking, pet policies, rental restrictions, special assessments, accessibility, and responsibility for windows or building systems.

An Olde Towne condominium or attached property may offer a similar opportunity to live near historic streets and the waterfront without maintaining an entire detached structure. The governing documents and financial health of the association remain critical.

Detached historic houses may provide more control, privacy, outdoor area, and architectural individuality, but they may also place more responsibility on the owner for roofing, exterior materials, drainage, landscaping, foundations, mechanical systems, and historically appropriate repairs.

For a deeper look at Ghent’s specific housing variety and buyer considerations, A Buyer’s Guide to Ghent in Norfolk, VA offers additional context on condos, townhomes, older houses, parking, maintenance, and daily convenience.

Which Community May Offer the Better Long-Term Fit?

Long-term fit depends on what the buyer wants the property to do.

Ghent may be worth prioritizing when the buyer’s routine is closely tied to Norfolk destinations and the available property offers an acceptable balance of condition, parking, ownership costs, and urban access.

Olde Towne may deserve greater focus when the buyer values Portsmouth’s waterfront, High Street, ferry connection, historic seaport setting, and the architectural character of a compact downtown community.

Resale should still be evaluated property by property. Features that may influence future marketability include condition, renovation quality, parking, floor plan, storage, natural light, outdoor usability, association finances, flood-zone status, insurance affordability, exterior maintenance, accessibility, and proximity to the destinations future buyers may value.

The most recognizable community name does not guarantee the strongest purchase. A thoughtfully updated Olde Towne property with practical parking may work better than a Ghent property with unresolved maintenance and an inconvenient layout—or the reverse may be true.

A Fair Housing-Minded Way to Compare Ghent and Olde Towne

A responsible community comparison should focus on objective housing, property, financial, and lifestyle information rather than assumptions about the people living in either location.

Useful factors include home type, price, condition, accessibility features, parking, commute route, public transportation, proximity to destinations selected by the buyer, flood information, insurance estimates, taxes, association obligations, renovation rules, storage, outdoor space, maintenance requirements, and recent comparable sales.

Buyers seeking information about schools, public services, transportation, crime statistics, future development, zoning, or environmental conditions should be directed to official and neutral sources so they can evaluate the information according to their own priorities.

The goal is not to label Ghent or Olde Towne as the community for a particular type of person. The goal is to help each buyer compare properties consistently and decide which home supports their own routine, budget, comfort, and plans.

How to Compare Available Homes in Both Communities

Start by choosing two or three properties in each location within a similar price range. Comparing actual homes is more useful than comparing community names in the abstract.

Review the list price, property type, square footage, layout, condition, renovations, permits, major-system ages, parking, flood information, insurance estimate, taxes, association dues, utilities, accessibility, storage, exterior responsibilities, and expected repairs.

Tour the surrounding blocks at more than one time of day. Test the commute, ferry, transit route, or walking path you would realistically use. Listen from inside and outside the property. Review where vehicles, bicycles, deliveries, trash containers, and guests would go.

Then calculate the complete ownership cost. A lower purchase price may not create a lower monthly or long-term cost if the property requires substantial maintenance, higher insurance, association assessments, immediate repairs, or historically appropriate exterior work.

The strongest conclusion is rarely that Ghent is better than Olde Towne or that Olde Towne is better than Ghent. It is that one specific property supports the buyer’s priorities more effectively than the alternatives currently available.

Frequently asked questions

Which is better for homebuyers: Ghent or Olde Towne Portsmouth?

Neither community is universally better. Ghent may offer a stronger connection to Norfolk’s commercial corridors, medical facilities, cultural destinations, downtown area, and employment centers. Olde Towne may offer a stronger connection to Portsmouth’s waterfront, High Street, ferry service, civic destinations, and historic seaport setting. The better choice depends on the exact property, price, condition, parking, commute, flood considerations, maintenance requirements, and total ownership cost.

Is Ghent or Olde Towne Portsmouth more walkable?

Both communities may support walking to selected restaurants, businesses, cultural destinations, public spaces, and services, but the usefulness of that access depends on the exact property and the destinations the buyer expects to use. Buyers should test their actual routes rather than relying on a general walkability label. Salyer Wilmoth Homes can help compare available properties based on the destinations and daily routines that matter to the buyer.

What types of historic homes can buyers find in Ghent and Olde Towne?

Available properties may include detached historic houses, attached residences, townhomes, condominiums, converted buildings, and renovated older homes. Inventory, condition, architectural style, outdoor space, parking, and association structure vary significantly. Buyers should compare individual properties rather than assuming every home in a historic district offers the same features or maintenance responsibilities.

Is Ghent or Olde Towne better for commuting to Norfolk?

Ghent may provide a more direct starting point for many Norfolk destinations because it is already within the city, but the actual commute depends on the property, destination, schedule, parking, and road conditions. Olde Towne offers road and transit connections to Norfolk, including Elizabeth River ferry service, but route timing should be tested. Share your work location and normal travel hours with Salyer Wilmoth Homes to compare realistic routes from currently available properties.

What should buyers inspect before purchasing a historic home in either community?

Buyers should closely review the roof, foundation, crawl space, moisture conditions, drainage, masonry, windows, electrical system, plumbing, HVAC equipment, insulation, renovation history, permits, lead-based paint disclosures when applicable, flood information, insurance estimates, and any historic-district restrictions. Depending on the property, specialized evaluations may also be appropriate. Salyer Wilmoth Homes can help buyers organize the property documents and inspection questions that deserve attention before an offer or during due diligence.


Thinking about Ghent or Olde Towne Portsmouth? Let’s compare available homes using the property condition, historic-district responsibilities, parking, routes, ownership costs, and daily-life details that matter to your plans.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Posted in Buyer Guides
Aug. 4, 2026

Military Relocation to Hampton Roads: PCS Guide

What do military families need to know before PCSing to Hampton Roads?

Military families PCSing to Hampton Roads need to move fast on three fronts: VA loan pre-approval, base housing coordination, and flood insurance. The region sits on one of the most flood-exposed coastlines on the East Coast, and many homes in Norfolk, Virginia Beach, Chesapeake, and Hampton fall inside FEMA Special Flood Hazard Areas where flood coverage must be in place before your loan closes. Starting those steps early is what keeps a tight PCS timeline from unraveling.

Why Hampton Roads Is Unlike Any Other Duty Station

Hampton Roads is home to one of the largest concentrations of military personnel in the United Stateswith Naval Station Norfolk (the world's largest naval base), NAS Oceana, Joint Base Langley-Eustis, Naval Air Station Joint Expeditionary Base Little Creek-Fort Story, and Coast Guard Base Portsmouth all operating in the same metro area. That means the local housing market is built around PCS cycles in a way that most duty stations simply aren't.

It also means local agents, lenders, and title companies have seen every wrinkle in a military move. But it does not mean the process is automatic. The coastal geography here introduces variables that inland duty stations never touch.

According to the Hampton Roads Planning District Commission's Coastal Resilience Program, Hampton Roads is one of the most vulnerable regions on the U.S. East Coast to coastal flooding and sea level rise. Tidal flooding, storm surge, and nuisance flooding affect streets and driveways even when a home itself sits at a safe elevation. I tell every buyer I work with here: the flood question isn't optional research. It's step one.

Choosing Where to Live Based on Your Installation

Where you buy should follow your commute. Here's how families typically sort it out:

  • Naval Station Norfolk: Norfolk neighborhoods like Ocean View, Ghent, and Larchmont are popular, along with parts of Chesapeake and Virginia Beach with direct interstate access.
  • NAS Oceana: Most families land in Virginia Beach, particularly areas off I-264 and Holland Road, for a manageable commute.
  • Joint Base Langley-Eustis: Hampton, Newport News, York County, and Poquoson are the typical clusters.

Each city has its own school division, its own property tax structure, and its own flood risk profile. The commute-plus-schools-plus-flood-risk calculation is something I walk every relocating family through before we even start looking at listings. If you want a deeper look at one specific area, my post on buying in Ocean View, Norfolk covers what coastal proximity really means for buyers near the bay.

Your VA Loan and the PCS Timeline

Virginia consistently ranks among the top states for VA home loan usageand Hampton Roads is a major driver of that activity. VA loans are an outstanding tool for military buyers, but a few rules matter especially when you're working against a PCS reporting date.

Occupancy and Deployment Rules

Under the VA Lenders Handbook (VA Pamphlet 26-7)you must intend to occupy the property as your primary residence, typically within 60 days of closing. If you're deployed at the time of closing, a spouse's occupancy can satisfy that requirement. This is worth confirming with your lender early, not after you're under contract.

I tell military families to line up VA loan guidance early so a PCS timeline never slows down their closing. That means getting your Certificate of Eligibility pulled, your lender selected, and your pre-approval letter in hand before you start touring homes, not after. In a competitive Hampton Roads market, a pre-approval letter isn't a formality. It's what gets your offer taken seriously.

What Virginia's Closing Process Looks Like

Virginia is a settlement attorney or title company statemeaning a closing attorney or title company handles the title search, insurance coordination, and settlement. According to Virginia REALTORS®a standard purchase contract includes negotiated contingencies for home inspection, appraisal, financing, and, where applicable, flood insurance or insurability. That last one matters a lot in Hampton Roads.

Your lender, settlement agent, and insurance agents all have to coordinate so that homeowners coverage and, if required, flood coverage are active at the moment of closing. Buyers on PCS orders also need to time closing so household goods delivery and base check-in fit inside the VA occupancy window. That's not a detail to figure out at the closing table.

Flood Insurance: The Step That Catches Military Buyers Off Guard

This is the part of a Hampton Roads purchase that surprises families coming from inland duty stations. Under the National Flood Insurance Program and related federal banking regulations, any federally regulated lender (including VA loan lenders) must require flood insurance if the property is in a FEMA Special Flood Hazard Area and flood insurance is available through the NFIP. That coverage must be in place at loan closing, not after.

In coastal Virginia, I always confirm flood insurance requirements before a buyer falls in love with a property. Discovering a flood requirement after you're under contract and two weeks from closing is a stressful situation that's entirely avoidable.

How to Check Before You Make an Offer

The FEMA Flood Map Service Center lets you look up any address against the current Flood Insurance Rate Maps (FIRMs). Your lender will also order an official flood zone determination as part of the loan process, but you don't have to wait for that. Check it yourself early. Large portions of Norfolk, Virginia Beach, Chesapeake, Portsmouth, and Hampton show up in SFHAs on current FEMA maps.

A few additional steps that can affect your closing timeline if you're in a flood zone:

  • Flood zone determination: Often handled by the lender or title company, but it needs to happen early in the transaction.
  • Flood insurance quote and policy issuance: Through the NFIP or a private Write-Your-Own insurer. Per FEMA's flood insurance guidance, there is no 30-day waiting period when coverage is required in connection with a new loan, which protects PCS buyers from that particular delay, but you still need time to get the quote, bind the policy, and get documentation to your lender.
  • Elevation certificate: If the insurer needs one to finalize the rating, a licensed land surveyor has to prepare it. Both the City of Norfolk and the City of Hampton advise property owners in SFHAs to obtain elevation certificates to document a home's elevation accurately. This can take time to order and receive.

Also worth knowing: Norfolk and Virginia Beach participate in FEMA's Community Rating Systemwhich can result in premium discounts on NFIP policies for policyholders in those jurisdictions. That's a detail worth asking your insurance agent about.

Get a homeowners insurance quote right after your offer is accepted, not in the final days before closing. In Hampton Roads, that means getting both a homeowners quote and a flood quote simultaneously if there's any chance the property is in or near a flood zone. The Virginia State Corporation Commission Bureau of Insurance is a useful resource if you have questions about carrier options or coverage requirements.

Coastal Nuances Beyond the FEMA Map

Here's something the map alone won't tell you: tidal flooding in parts of Norfolk, Hampton, and Virginia Beach affects streets and driveways even when a home sits above the base flood elevation. The Hampton Roads Planning District Commission has published ongoing sea level rise studies that affect how local practitioners think about long-term risk, not just whether a property technically requires flood insurance today.

I also pay attention to road access in storm events, proximity to evacuation routes, and whether a property is behind a levee or flood wall (which affects how it's mapped). If you're looking near NAS Oceana, there's an additional layer: noise zones from runway approaches can affect livability and, in some cases, local land-use policies. My post on waterfront proximity risk and lifestyle in Norfolk and Virginia Beach goes deeper on what coastal buyers need to weigh.

Base Resources and First Steps When Orders Arrive

The Navy Region Mid-Atlantic Housing Service Centers at Naval Station Norfolk, NAS Oceana, and Joint Expeditionary Base Little Creek-Fort Story provide counseling on both on-base and off-base housing, and they can help you map your options to your reporting date. Contact them as soon as orders arrive, especially if you're moving during peak PCS months (late spring through summer), when both the housing market and insurance underwriting timelines get compressed.

Army and Air Force families at Joint Base Langley-Eustis can access the Relocation Readiness Program for similar support, including cost-of-living guidance and home-finding services across the broader Hampton Roads area.

The Virginia Department of Veterans Services also maintains resources for military families and veterans navigating the region, and Hampton Roads has multiple veteran support facilities clustered here precisely because of the density of installations.

On the school side: Hampton Roads is served by multiple independent school divisions, and each requires proof of residency, immunization records, and prior school records at registration. Virginia law provides specific protections for military-connected students to ease transitions and ensure coursework continuity when families move between divisions. Timing your closing so kids can start school on schedule is something I help families plan for, not just the transaction itself.

Installation Common Residential Areas School Division Key Flood Consideration
Naval Station Norfolk Ocean View, Ghent, Larchmont (Norfolk); parts of Chesapeake and Virginia Beach Norfolk Public Schools; Chesapeake or VBCPS depending on address Norfolk has extensive SFHA zones; tidal flooding common near Elizabeth and Lafayette Rivers
NAS Oceana Virginia Beach (I-264 corridor, Holland Road area) Virginia Beach City Public Schools Portions of Virginia Beach in SFHA; noise zone overlay near runway approaches
Joint Base Langley-Eustis Hampton, Newport News, York County, Poquoson Hampton City Schools; Newport News, York County, or Poquoson depending on address Hampton and Poquoson have significant coastal flood exposure; elevation certificates often needed

Frequently Asked Questions

How do I use a VA loan to buy near Naval Station Norfolk or NAS Oceana without missing my PCS reporting date?

Get your VA loan pre-approval and Certificate of Eligibility pulled before you start touring homes. Contact the Navy Region Mid-Atlantic Housing Service Center as soon as orders arrive to understand on-base availability and off-base timelines. Then work with a local agent who knows how to build a contract timeline that accounts for flood zone determinations, insurance underwriting, and the VA occupancy requirement, all of which need to close before your reporting date.

Do I need flood insurance to buy in Virginia Beach, Norfolk, or Chesapeake with a VA loan?

It depends on the specific property. The VA loan program itself doesn't mandate flood insurance, but federal law requires it if the property is in a FEMA Special Flood Hazard Area and your lender is federally regulated, which VA lenders are. Use the FEMA Flood Map Service Center to check any address before you make an offer. Large portions of all three cities fall in SFHAs, so this is a real possibility, not a remote one.

What base resources help military families find housing when they PCS to Hampton Roads?

Navy installations in Hampton Roads operate Housing Service Centers and Relocation Assistance Programs at Naval Station Norfolk, NAS Oceana, and Joint Expeditionary Base Little Creek-Fort Story. Army and Air Force families at Joint Base Langley-Eustis can use the Relocation Readiness Program. These offices help you weigh on-base versus off-base options and align your housing decision with your reporting date. Contact them immediately when orders arrive, not after you've already started searching online.

Are there school enrollment protections for military kids moving into a Hampton Roads school district?

Virginia law includes specific protections for military-connected students to ease transitions between school divisions and maintain coursework continuity. Each Hampton Roads city runs its own independent school division, so enrollment requirements (proof of residency, immunization records, prior school records) apply at the division level. Timing your closing so children can enroll on schedule takes planning, and it's something a local agent familiar with PCS moves can help you coordinate.

How long does it take to line up flood insurance for a Hampton Roads home purchase?

When flood coverage is required in connection with a new loan, the standard 30-day NFIP waiting period does not apply, per FEMA's flood insurance guidelines. Even so, you need time to get the flood zone determination, obtain quotes, bind the policy, and, if required, order an elevation certificate from a licensed surveyor. Starting this process at contract rather than at the end of your inspection period is what keeps it from becoming a closing-day bottleneck.

The Bottom Line for Military Families Heading to Hampton Roads

A PCS move to Hampton Roads is manageable when you start the right steps in the right order: VA loan pre-approval, base housing counseling, flood zone research, and insurance underwriting all need to happen in parallel, not sequentially. The families I've worked with who had the smoothest closings were the ones who treated the flood question as part of the home search, not an afterthought.

My team at Salyer Wilmoth Homes specializes in exactly this kind of move. We know the installations, the neighborhoods, the flood maps, and the PCS timelines. If you've received orders to Hampton Roads and want to talk through your options, call or text me directly at 757-502-3671. Let's build a plan that gets you into the right home before your reporting date.

About Michele Salyer

Michele Salyer is a top-producing REALTOR® serving Southeast Virginia and Northeast North Carolina, helping buyers and sellers make confident moves with more than 20 years of combined real estate and paralegal experience. She is a Broker licensed in both Virginia (Lic. VA 0225238875) and North Carolina (Lic. NC 322300), and leads the Salyer Wilmoth Homes team at Atlantic Sotheby's International Realty.

Atlantic Sotheby's International Realty · 757-502-3671

Equal Housing Opportunity. Michele Salyer, Realtor/Broker Licensed in Virginia (VA 0225238875) and North Carolina (NC 322300), regulated by the Virginia Real Estate Commission and the North Carolina Real Estate Commission. This article is general information only and is not legal, tax, or financial advice. Confirm all details specific to your transaction with your attorney, tax advisor, lender, or closing officer.

Aug. 3, 2026

What Happens if a Virginia Home Appraises Below the Offer Price?

TL;DR

When a Virginia home appraises below the accepted offer price, the sale does not automatically end, but the lender may reduce the amount it is willing to finance, creating an appraisal gap that the buyer and seller must resolve by reviewing the report for errors, requesting a reconsideration of value when credible market evidence supports one, renegotiating the purchase price, dividing the difference between the parties, adjusting the buyer’s financing, bringing additional approved funds to closing, or terminating the transaction when the signed contract and applicable financing provisions allow it; because a pre-approval does not guarantee that a specific property will support the requested loan amount, buyers should immediately review their appraisal, financing contingency, appraisal language, earnest-money exposure, available reserves, lender requirements, and contract deadlines with their real estate and lending professionals before agreeing to cover any difference, while sellers should compare the cost of a reasonable price adjustment with the uncertainty of returning to the market and potentially receiving another appraisal at a similar value.

What Does It Mean When a Home Appraises Below the Offer Price?

A low appraisal occurs when the appraiser’s opinion of the property’s market value is lower than the price stated in the ratified purchase agreement.

For example, imagine that a buyer agrees to purchase a Virginia Beach home for $475,000, but the appraisal supports a value of only $455,000. The difference between the contract price and appraised value is a $20,000 appraisal gap.

An appraisal is an independent opinion of value prepared for the mortgage transaction. It typically considers the home’s condition, location, size, improvements, market activity, and comparable sales, but it is not a home inspection, a guarantee of future value, or a statement that the buyer and seller were unreasonable to agree on a different price.

The appraisal primarily helps the lender evaluate the property serving as collateral for the mortgage. When the value does not support the planned financing, the lender may decline to approve the original loan amount or require the financing structure to change. A lender may not approve the loan—or may not lend the full requested amount—when the appraisal is below the purchase price.

This can surprise buyers who already received a strong pre-approval. Pre-approval evaluates the borrower’s ability to qualify for financing, while the appraisal evaluates the specific property. Buyers who are still preparing to make offers may benefit from reviewing One Homebuying Step You Don’t Want to Skip: Pre-Approval, but they should remember that even a fully qualified borrower still needs the selected home to meet the lender’s valuation requirements.

Does a Low Appraisal Automatically Cancel the Virginia Purchase Contract?

No. A low appraisal does not automatically cancel a Virginia real estate contract, force the seller to reduce the price, or allow every buyer to walk away without consequences.

What happens next depends on the language of the signed purchase agreement, any appraisal or financing contingency, the buyer’s loan program, whether the buyer agreed to cover a specified appraisal gap, and whether the applicable deadlines have been met.

Some buyers submit offers that are contingent on the property appraising at or above a particular value. Others agree to contribute a limited amount above the appraised value. A buyer may also waive or narrow certain appraisal protections to make an offer more competitive.

Those choices can materially affect the buyer’s options. A buyer who has a valid appraisal or financing protection may be able to renegotiate or terminate under the contract’s terms. A buyer who waived relevant protections may still be contractually obligated to close, even when the lender will not finance the entire anticipated amount.

Failing to close without a contractual basis could place the buyer’s earnest-money deposit at risk and may create other potential consequences. Buyers should not assume that a financing denial, appraisal shortage, or verbal disagreement automatically releases them from the contract. The precise language and notice deadlines should be reviewed promptly with the appropriate real estate and legal professionals.

How Does a Low Appraisal Affect the Buyer’s Mortgage?

The lender does not usually increase the collateral value simply because the buyer offered more than the appraisal supports.

Instead, the lender reviews the loan using the appraised value, purchase price, down payment, loan-to-value ratio, mortgage program, mortgage-insurance requirements, and underwriting guidelines. That review may change the approved loan amount or the amount of cash the buyer must bring to settlement.

Suppose a buyer agreed to pay $500,000 and planned to borrow $450,000. If the property appraises for $480,000, the lender may no longer be able to approve the original loan on the same terms. The buyer might need to increase the down payment, accept mortgage insurance, change loan products, reduce the purchase price, or combine more than one solution.

The amount of additional cash required is not always identical to the full appraisal gap. It depends on how much the lender will finance under the revised value and loan guidelines. Buyers should ask the lender for updated written figures rather than assuming that a $20,000 appraisal gap automatically means exactly $20,000 more is due at closing.

This is also where reserves matter. A buyer may technically have enough money to cover the difference but leave little available for moving, repairs, insurance deductibles, emergencies, or ordinary ownership costs. Before using savings to preserve the deal, buyers should review How Much Cash Should First-Time Buyers Keep After Closing? and consider whether the purchase will remain financially comfortable after settlement.

What Options Does a Virginia Buyer Have After a Low Appraisal?

The buyer’s first step should be to obtain and carefully review the appraisal. For most first-lien mortgage applications, the creditor must provide the borrower with a copy of the completed appraisal or other written valuation promptly upon completion or no later than three business days before closing, subject to the rule’s permitted timing waiver.

After reviewing the report and the contract, several possible responses may be available.

Ask the seller to reduce the purchase price. The buyer may request that the seller lower the price to the appraised value. The seller is not automatically required to agree, but the appraisal gives both parties a documented basis for reopening the price discussion. The CFPB identifies negotiating a lower sale price as a common next step after an appraisal comes in below the contract amount.

Negotiate a partial price reduction. The seller may reduce the price by part of the difference while the buyer contributes additional funds for the remainder. This approach can preserve the transaction without requiring either party to absorb the entire gap.

Bring additional funds to closing. When the contract, lender, and buyer’s financial position allow it, the buyer may pay more cash to complete the purchase. Before doing so, the buyer should determine whether the home is worth that amount to them, whether sufficient reserves will remain, and whether paying above the appraisal could affect future resale or refinancing plans.

Adjust the financing. Depending on the loan program and borrower qualification, the lender may be able to restructure the down payment, loan amount, mortgage insurance, credits, or other approved terms. A buyer should not move funds, borrow money, or open a new credit account without first consulting the lender, because undocumented or newly borrowed funds may create additional underwriting problems.

Request a reconsideration of value. When the appraisal appears to contain material errors, omit relevant property features, or overlook stronger comparable sales, the borrower can ask the lender about its reconsideration-of-value process. Current Fannie Mae requirements call for lenders to maintain procedures for borrower-initiated reconsideration requests while preserving appraiser independence.

Terminate the transaction when permitted. A buyer may have the right to end the contract if an applicable appraisal, financing, FHA, or VA provision has been properly invoked. Whether the earnest-money deposit is returned depends on the specific contract, loan provisions, notices, deadlines, and circumstances.

Can a Buyer Challenge a Low Appraisal?

Yes, but a reconsideration of value should be based on specific evidence rather than disappointment with the result.

A productive review begins by checking the report for factual inaccuracies. The buyer, agent, and lender may examine whether the appraisal misstated the square footage, bedroom or bathroom count, lot size, property type, condition, renovations, parking features, permitted additions, waterfront characteristics, or other relevant details.

The parties may also identify comparable sales that were available as of the appraisal’s effective date but were not considered. Strong comparable sales are generally similar in location, property type, size, condition, quality, features, and timing. A nearby home is not automatically a useful comparable simply because it sold for a higher price.

The request should clearly explain why the proposed information may affect the value. Statements such as “the buyer loves the house,” “the seller needs this amount,” or “another buyer might have paid more” do not establish market value.

The lender manages communication with the appraiser to protect appraisal independence. Buyers and agents should not pressure, threaten, or attempt to influence the appraiser to reach the contract price. Federal valuation-independence rules prohibit improper coercion or alteration of an appraiser’s genuine opinion of value.

A reconsideration may result in a correction or higher value, but it may also confirm the original appraisal. The parties should continue evaluating their contractual and financial options rather than assuming that a challenge will necessarily close the gap.

What Happens When a VA Appraisal Comes In Low?

A VA appraisal follows program-specific procedures and determines the property’s reasonable value for VA loan-guaranty purposes. The loan amount cannot simply exceed the value supported under the VA program.

When a VA appraiser believes the property may not support the contract price, the Tidewater Initiative may allow the designated point of contact to provide relevant sales information before the appraisal is finalized. If the completed value still does not support the transaction, VA identifies several possible options: request a Reconsideration of Value through the lender, renegotiate the sales price, or pay the difference between the appraised value and contract price at closing.

VA transactions also include appraisal-related protections commonly addressed through the required escape-clause language. The precise form and effect should be reviewed with the lender and real estate professional before the buyer makes any decision about paying above the VA value.

A low VA appraisal does not mean VA financing is inherently weak or that every VA offer is likely to face a valuation problem. It means the parties must respond through the VA process and the terms of the purchase agreement. Military buyers who want to prepare before making an offer can review How First-Time Military Buyers Can Strengthen Their Offer When Using a VA Loan for a broader look at financing readiness, contract structure, communication, and offer strategy.

What Happens When an FHA Appraisal Comes In Low?

FHA-financed transactions generally include an amendatory clause stating that the purchaser is not obligated to complete the purchase or forfeit earnest money solely because the property does not appraise at or above the value stated in the clause.

The clause does not prohibit the buyer from proceeding. The buyer may voluntarily continue with the purchase despite the lower appraisal, provided the lender approves the final financing arrangement and any additional funds comply with FHA and underwriting requirements. HUD’s model language specifically preserves the purchaser’s option to complete the contract regardless of the appraised valuation.

The seller may reduce the price, the parties may renegotiate other permitted terms, or the buyer may elect not to proceed under the applicable FHA protection. Because FHA requirements and the private purchase contract work together, the buyer should obtain instructions from the FHA lender and real estate professional before signing an amendment or releasing any contingency.

Should a Seller Reduce the Price After a Low Appraisal?

A seller is not automatically required to lower the contract price, but refusing to negotiate may not always produce a stronger financial outcome.

The seller should examine the appraisal carefully, compare it with recent market evidence, and consider whether a different financed buyer could encounter the same valuation issue. A future appraisal could be higher, lower, or similar, but relisting does not guarantee that the next buyer or lender will support the original price.

The seller should also consider the cost of returning to the market. Additional mortgage payments, utilities, insurance, maintenance, staging, showing disruption, price reductions, and buyer uncertainty can outweigh part of the appraisal difference.

On the other hand, a seller may have legitimate evidence that the appraisal missed important property characteristics or stronger comparable sales. In that case, supporting a well-documented reconsideration request may be reasonable before changing the price.

A low appraisal negotiation should be based on expected net proceeds, market evidence, buyer qualification, contract deadlines, and the likelihood of reaching closing. Sellers deciding whether to adjust the price or offer a different financial solution may also find Price Reduction or Closing-Cost Credit: Which Gets More Buyer Attention? helpful, although a closing-cost credit does not replace the need for the contract price and loan structure to satisfy the lender’s valuation requirements.

Should the Buyer Pay More Than the Appraised Value?

Paying above the appraisal is not automatically a mistake, but it should be a deliberate decision.

An appraisal is an opinion based on available data and a defined effective date. A buyer may reasonably place additional value on a particular location, floor plan, lot, renovation, commute, or lack of comparable inventory. However, personal preference does not change the lender’s collateral calculation.

Before covering a gap, the buyer should ask:

Does the purchase still leave adequate emergency and ownership reserves?

Would paying the difference require high-interest debt or an unapproved source of funds?

How long does the buyer expect to own the property?

Would the buyer remain comfortable if prices stayed flat for several years?

Does the home need repairs, replacements, or immediate maintenance?

Could insurance, taxes, HOA dues, flood coverage, or other expenses place additional pressure on the budget?

The contract price is only one part of affordability. Extra Costs That Can Surprise Buyers Near Coastal Virginia explains how insurance, escrow deposits, association charges, moving expenses, coastal maintenance, and other costs can change the financial picture after closing.

A buyer should not exhaust savings merely because the transaction has reached the appraisal stage. Walking away may feel disappointing when the contract allows it, but closing without adequate reserves can create a much longer financial problem.

Why Appraisal Deadlines Matter

Low-appraisal decisions often need to be made quickly.

The contract may establish deadlines for delivering the appraisal notice, requesting a price change, providing evidence of the lender’s determination, invoking a financing provision, or terminating the agreement. VA, FHA, and conventional lenders may also have their own processing timelines for appraisal reviews and reconsideration requests.

Waiting can reduce the buyer’s options. An otherwise valid protection may be lost when required notice is late, incomplete, or delivered incorrectly.

The buyer should contact the lender and agent immediately after receiving the appraisal. The parties should identify the exact gap, updated loan amount, additional funds required, contract deadline, earnest-money implications, and evidence available for a reconsideration before selecting a strategy.

Verbal conversations are not a substitute for properly drafted and delivered written amendments or notices. Any change to the price, seller contribution, closing date, financing, or appraisal-gap obligation should be documented in accordance with the contract and lender requirements.

Keep the Appraisal Process Fair Housing-Minded

Appraisal reviews and negotiations should focus on the property, contract, financing, comparable sales, verified improvements, and objective market evidence—not on who lives in an area or the personal characteristics of buyers, sellers, or residents.

Virginia’s Fair Housing Law applies to residential sales, financing, insurance, and advertising. It prohibits discrimination based on race, color, religion, national origin, sex, elderliness, familial status, disability, source of funds, sexual orientation, gender identity, and military status. It also prohibits applying different standards to people because of a protected characteristic.

Comparable-sale discussions should avoid demographic descriptions, assumptions about the people living in a neighborhood, or coded statements about who an area is “for.” The analysis should remain centered on legitimate property and market factors.

Similarly, sellers should evaluate offers and appraisal solutions using consistent, lawful criteria such as price, financing, appraisal-gap terms, contingencies, deposit, timing, and documented ability to close.

Frequently asked questions

What happens if the appraisal is lower than the offer price in Virginia?

The lender may reduce the amount it is willing to finance, creating a gap between the approved financing and the contract price. The buyer and seller may renegotiate the price, split the difference, request a reconsideration of value, change the financing when permitted, or have the buyer contribute additional approved funds. The buyer may also be able to terminate the transaction, but that depends on the signed contract, appraisal or financing provisions, loan program, and applicable deadlines.

Can a Virginia buyer back out after a low appraisal?

A Virginia buyer may be able to terminate after a low appraisal when the purchase contract, appraisal contingency, financing contingency, FHA clause, or VA provision gives the buyer that right and the required notice is delivered on time. A buyer who waived relevant protections may have fewer options and could place the earnest-money deposit at risk by refusing to close. Salyer Wilmoth Homes can help buyers identify the relevant contract language and coordinate questions with the lender and settlement professionals before a deadline passes.

Does the buyer have to pay the entire appraisal gap in cash?

Not necessarily. The amount of additional cash depends on the appraised value, purchase price, original down payment, revised loan-to-value ratio, mortgage program, lender requirements, and any price reduction negotiated with the seller. The lender should provide updated figures showing the approved loan amount and estimated cash to close. Buyers should not assume the contract-price difference is automatically identical to the additional amount they must bring.

Can you challenge a low home appraisal in Virginia?

Yes. A buyer can ask the lender about requesting a reconsideration of value when the report contains factual errors, excludes material property features, or appears to overlook stronger comparable sales available as of the appraisal date. The request should include specific, verifiable information rather than pressure to reach the contract price. Salyer Wilmoth Homes can help organize relevant property details and potential comparable-sale information for the lender’s review, while the lender controls the formal appraisal communication.

What happens if a VA or FHA appraisal comes in below the purchase price?

A VA buyer may ask the lender about Tidewater information or a Reconsideration of Value, renegotiate the price, contribute approved funds toward the difference, or rely on applicable VA contract protections. An FHA buyer may use the applicable amendatory-clause protection, renegotiate, or voluntarily proceed despite the lower value when the lender approves the final financing. Buyers using either program should consult the lender before signing an amendment or agreeing to cover a gap. Salyer Wilmoth Homes can help coordinate the contract and appraisal conversation with a VA- or FHA-experienced lender.

This article provides general real estate information and is not legal, appraisal, lending, tax, or financial advice. Contract rights, financing requirements, and appraisal procedures vary according to the transaction. Buyers and sellers should consult their lender, settlement provider, attorney, appraiser, and other appropriately licensed professionals about their specific circumstances.


Received a low appraisal on a Coastal Virginia home? Let’s review the property, contract deadlines, lender figures, and available negotiation paths before you decide what comes next.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity
Posted in Buyer Guides
July 31, 2026

What Happens if You Deploy Before Your Home Purchase Closes?

TL;DR

Deploying before your home purchase closes does not necessarily end the transaction, but it can affect how documents are signed, how the lender verifies your employment and occupancy plans, who completes the final walkthrough, how closing funds are transferred, and whether a power of attorney or another approved remote-closing method can be used, so the safest response is to notify your lender, real estate agent, settlement or title company, insurance professional, and any co-buyer immediately; confirm that the purchase still meets the loan program’s occupancy and underwriting requirements; arrange a lender- and settlement-approved power of attorney before departure when appropriate; preserve secure access to email, identification, financial records, military orders, and closing documents; identify a trusted person who can inspect the property or attend the walkthrough; and review every contract deadline rather than assuming deployment orders automatically pause or cancel the purchase.

Deployment Does Not Automatically Cancel the Purchase

A deployment notice can arrive while a buyer is under contract, completing inspections, waiting for an appraisal, resolving title questions, or approaching settlement. The timing may feel as though the transaction has become impossible, but deployment does not automatically prevent a home purchase from closing.

The outcome depends on several property- and transaction-specific factors:

  • The terms of the purchase agreement

  • The type of mortgage

  • The lender’s underwriting requirements

  • The buyer’s intended occupancy

  • Whether another borrower will occupy the property

  • The stage of the loan

  • The settlement company’s signing procedures

  • State notarization and recording requirements

  • Whether a valid power of attorney has been prepared

  • Whether the deployment changes the buyer’s income, duty station, housing allowance, or financial obligations

The first priority is not deciding whether to cancel. It is determining what has changed and which members of the transaction team need to approve a revised closing plan.

Military buyers already facing a compressed relocation schedule may also benefit from reading Don’t Let a PCS Rush Your Home Purchase: What Can Go Wrong When You Buy Too Fast, because a deployment should not pressure a buyer into skipping property research, inspections, document review, or financial safeguards.

Tell the Lender as Soon as Deployment Becomes Likely

The lender should learn about the deployment directly from the buyer, not at the final signing appointment.

Mortgage approval is based on information about employment, income, assets, debts, occupancy, and the intended use of the property. A deployment may not negatively change those factors, but the lender still needs enough information to determine whether the file remains accurate.

The lender may ask for:

  • Military orders or other documentation

  • Updated leave and earnings statements

  • Confirmation of active-duty status

  • Updated bank statements

  • Clarification regarding Basic Allowance for Housing

  • A revised explanation of occupancy

  • Information about a spouse or co-borrower

  • Contact information during deployment

  • A power of attorney for review

  • Additional verification shortly before closing

Do not assume that being fully approved means no further verification will occur. Mortgage lenders may continue requesting documents during underwriting and before funding. CFPB guidance advises buyers to remain alert for lender requests throughout the closing phase and notes that changes to financial information can affect parts of the loan process.

The buyer should ask the loan officer directly:

  • Does the deployment affect my approval?

  • Will my income be calculated differently?

  • Does my occupancy explanation need to be updated?

  • Can the scheduled closing date remain in place?

  • What type of power of attorney will the lender accept?

  • Must the lender approve the document before it is signed?

  • Will any additional certification be required on closing day?

  • Which documents must I personally sign?

A vague assurance that remote closing “should be fine” is not enough. The buyer should obtain a specific plan from the lender and settlement company.

Confirm How Deployment Affects Occupancy

Occupancy deserves special attention when a VA-backed purchase loan is involved.

VA describes its home-loan benefit as supporting the purchase of a home for the borrower’s personal occupancy. Its current guidance also states that VA-guaranteed purchase loans may be available for a home occupied by the servicemember or, for an active-duty servicemember, by a spouse or dependent. The lender must still evaluate the specific facts and document the transaction appropriately.

A deployment may not eliminate the original intent to use the property as a primary residence. However, the buyer should not make assumptions about how the lender will interpret delayed occupancy, dependent occupancy, an unaccompanied assignment, or a change in duty station.

Discuss questions such as:

  • Who will occupy the home after closing?

  • When was the buyer originally expected to move in?

  • Is a spouse or dependent moving into the property?

  • Is the deployment temporary?

  • Has the buyer received different orders from those used during loan approval?

  • Will the home remain the buyer’s intended primary residence?

  • Has the property effectively become a second-home or investment purchase?

The buyer should give the lender an accurate explanation rather than trying to preserve the transaction through incomplete information. Occupancy representations are part of the loan file and should reflect the actual plan.

Military buyers who are still deciding whether ownership fits their current assignment can use PCSing to Naval Station Norfolk: Should You Buy Right Away? to compare timing, expected length of stay, total cost, commute, and the value of renting first.

A Power of Attorney May Allow Someone Else to Sign

A power of attorney is a legal document that authorizes another person—the agent or attorney-in-fact—to act for the buyer within the authority described in the document. CFPB identifies a power of attorney as one method servicemembers may use to delegate financial decisions during deployment.

However, not every power of attorney will be accepted for a real estate closing.

The lender, settlement company, title insurer, and recording office may have detailed requirements involving:

  • The names of the buyer and agent

  • The property address or legal description

  • The specific transaction

  • Authority to sign the promissory note

  • Authority to sign the deed of trust or mortgage

  • Authority to sign settlement documents

  • Authority to receive notices

  • The document’s effective date and expiration

  • Notarization

  • Witness requirements

  • Recording of the power of attorney

  • Original-document requirements

  • Lender review and approval

Some transactions require a specific or limited power of attorney rather than a broad general document. A standard deployment power of attorney that works for banking or vehicle matters may not contain the authority required for a mortgage closing.

The buyer should send the proposed document to the lender and settlement company before signing it. Preparing the wrong document shortly before departure can create a delay that is difficult to correct from another location or time zone.

VA Loans May Require Additional Power-of-Attorney Verification

VA permits a power of attorney to be used under applicable requirements, but the lender has additional responsibilities.

VA’s lender materials state that when a power of attorney is used, the lender must verify that the Veteran is alive and, when on active military duty, not missing in action. The lender completes a power-of-attorney certification, sometimes referred to as a “live and well” certification.

That certification is separate from the power of attorney itself.

Military buyers using VA financing should ask:

  • Who will complete the required certification?

  • When will the lender verify the buyer’s status?

  • Does the servicemember need to be reachable on closing day?

  • What communication method is acceptable?

  • What happens if operational conditions prevent contact?

  • Does the power of attorney expressly authorize the VA loan transaction?

  • Must the sales contract or loan application contain the buyer’s personal signature?

The practical concern is communication. A legally sufficient document may still be difficult to use if the lender cannot complete a required closing-day verification.

Build a backup communication plan before deployment rather than assuming internet or telephone access will be consistently available.

Remote Signing May Be Possible Without a Power of Attorney

Some buyers may be able to sign closing documents remotely rather than appointing another person.

Possible arrangements can include:

  • Electronic signing for eligible documents

  • A mobile notary

  • Remote online notarization where permitted

  • A mail-away closing package

  • Signing at a military legal office

  • Signing at a U.S. embassy or consular location when available

  • Signing documents before departure and placing them in escrow

  • A hybrid closing in which some documents are electronic and others are signed on paper

Availability depends on the lender, settlement company, title insurer, property location, document type, and recording rules. Certain mortgage documents may require notarization or original signatures even when other documents can be signed electronically.

Ask for a document-by-document explanation:

  • Which papers can be electronically signed?

  • Which require notarization?

  • Which require an original signature?

  • Where will the signed documents be delivered?

  • How much time should be allowed for shipping?

  • Will a delay in receiving originals delay funding or recording?

  • Can the documents be prepared early?

  • What identification will the signer need?

A buyer should not assume that a “remote closing” means every step can be completed through one email link.

Contract Deadlines Usually Continue

Deployment does not automatically erase the dates in a ratified purchase agreement.

The contract may contain deadlines for:

  • Earnest-money delivery

  • Loan application

  • Financing approval

  • Home inspection

  • Repair requests

  • HOA or condominium review

  • Title objections

  • Appraisal

  • Insurance

  • Survey

  • Final walkthrough

  • Closing

  • Possession

If deployment affects one of these deadlines, the parties may need a written amendment. A conversation with the agent or seller does not necessarily change the contract.

The buyer should ask the real estate agent and, when appropriate, a qualified attorney to identify:

  • Which deadlines remain open

  • Which tasks require the buyer’s personal participation

  • Which rights expire if no action is taken

  • Whether an extension is needed

  • Whether the seller must agree

  • What happens if lender approval is delayed

  • What happens if the buyer cannot complete the transaction

  • Whether a military-orders provision exists in the contract

Official SCRA resources describe protections involving matters such as certain pre-service debts, residential leases, foreclosure, eviction, repossession, and court proceedings. Buyers should seek military legal assistance rather than assuming those protections automatically cancel or suspend a pending real estate purchase agreement.

Do Not Skip the Inspection or Property Review

Deployment may make it harder to participate in the home inspection, but it does not make the property’s condition less important.

The buyer can often arrange for:

  • A spouse or co-buyer to attend

  • The real estate agent to attend when permitted

  • A trusted representative to attend

  • A video call with the inspector

  • Photographs and video of specific findings

  • A detailed written report

  • Follow-up evaluations by contractors or specialists

  • Electronic repair negotiations

The representative should understand the buyer’s concerns and not simply report that the home “looked fine.”

Ask the inspector to document:

  • Roof and exterior conditions

  • Foundation or crawl-space concerns

  • Moisture and drainage

  • Electrical and plumbing systems

  • HVAC equipment

  • Visible structural concerns

  • Safety issues

  • Signs of deferred maintenance

  • Areas that were inaccessible

  • Recommended specialist evaluations

A rushed timeline can make uncertain improvements particularly risky. How Can Buyers Tell Whether an Addition Was Properly Permitted? explains why a finished room, converted garage, enclosed porch, or expanded living area may require permit, inspection, square-footage, appraisal, and insurance research before closing.

Create a Detailed Final-Walkthrough Plan

The final walkthrough is the buyer’s opportunity to confirm that the property remains in the agreed condition shortly before closing.

CFPB recommends completing a walkthrough before signing to verify that agreed repairs were completed and that items the seller agreed to leave remain at the property.

When the buyer is deployed, the walkthrough may be completed by a co-buyer, agent, or properly authorized representative, depending on the transaction.

The person completing it should verify:

  • The seller has moved out as agreed

  • Required repairs appear complete

  • Included fixtures and appliances remain

  • The property has not suffered new damage

  • Utilities are operating when required

  • Plumbing fixtures function

  • Heating or cooling can be tested when practical

  • Windows and exterior doors are secure

  • No unexpected personal property or debris remains

  • The garage, attic, crawl space, sheds, and exterior are accessible

  • Keys, remotes, codes, and documents will be delivered

Ask for timestamped photographs or a live video walkthrough. The representative should immediately report any material change to the buyer, agent, and settlement team.

Keep Insurance Moving Before Deployment

Homeowners insurance is generally required by the mortgage lender before closing. Deployment can complicate communication with the insurance company, particularly if additional property information or documents are requested.

Before departure, confirm:

  • The insurer has the correct property address

  • The policy’s effective date matches closing

  • The lender is listed correctly

  • The coverage amount satisfies lender requirements

  • The insurer knows how the home will be occupied

  • Any vacancy or delayed-move-in question has been disclosed

  • Flood insurance has been addressed when applicable

  • The premium and deductible fit the buyer’s budget

  • The binder or evidence of insurance has been sent to the lender

Do not describe the property as owner-occupied on an insurance application without explaining the real post-closing arrangement. The insurer should understand whether a spouse or dependent will occupy the home, whether the house will initially be vacant, and when the deployed buyer expects to return.

An unresolved insurance issue can delay loan approval even when the appraisal and underwriting are otherwise complete.

Protect the Closing Funds From Wire Fraud

Deployment creates ideal conditions for scammers: time-zone differences, changing contact information, limited phone access, urgent emails, and reliance on remote communication.

CFPB warns that criminals may impersonate a real estate or settlement professional and send fraudulent last-minute wiring instructions. Buyers should independently verify instructions using a trusted telephone number rather than replying to the suspicious message.

Before departure:

  • Confirm who will provide wiring instructions

  • Save verified telephone numbers offline

  • Ask whether instructions are delivered through a secure portal

  • Establish a verification password or process

  • Tell the settlement company who is authorized to communicate

  • Confirm whether closing funds may come from the agent under a power of attorney

  • Verify transfer limits with the bank

  • Avoid making a first-time wire from an unfamiliar device or network

  • Never rely solely on emailed account details

If wiring instructions change, stop. Call the settlement company using the number already verified before the change.

Review the Closing Disclosure From Wherever You Are

For most covered mortgages, the lender must provide the Closing Disclosure at least three business days before closing. The form contains the final loan terms, projected payment, cash to close, and closing costs.

Deployment does not reduce the importance of reviewing it.

Compare the Closing Disclosure with the most recent Loan Estimate and check:

  • Borrower names

  • Property address

  • Loan type

  • Loan amount

  • Interest rate

  • Monthly principal and interest

  • Estimated taxes and insurance

  • Escrow details

  • Discount points or lender credits

  • Seller-paid costs

  • Cash to close

  • Closing date

  • Prepayment terms

  • Fees that changed

  • Credits negotiated in the contract

Send questions immediately. A buyer should not ask an agent under a power of attorney to sign documents that the buyer has not reviewed and understood.

CFPB also notes that active-duty servicemembers may be able to obtain contract review assistance through an installation legal office.

Keep the Loan Financially Stable Before Closing

Deployment preparation can lead to major financial activity: travel purchases, household moves, storage, vehicle arrangements, new accounts, large deposits, or credit-card use.

Before the loan funds, avoid making unexplained financial changes without discussing them with the lender.

This may include:

  • Opening a new credit account

  • Financing furniture or a vehicle

  • Closing an established account

  • Moving large amounts between accounts

  • Depositing cash that cannot be documented

  • Co-signing another loan

  • Missing a payment

  • Changing how closing funds are held

  • Allowing identification to expire

  • Changing banks without warning

Deployment itself may not harm the mortgage approval, but an unexplained debt, asset change, or payment issue may create underwriting questions.

Maintain accessible copies of:

  • Military orders

  • Leave and earnings statements

  • Bank statements

  • Tax documents

  • Identification

  • Certificate of Eligibility when using a VA loan

  • Purchase agreement and amendments

  • Inspection report

  • Insurance documents

  • Power of attorney

  • Lender and settlement contact information

Use secure storage rather than sending sensitive documents through unencrypted personal messages.

Decide Who Will Manage the Home After Closing

Closing is not the end of the deployment plan.

The buyer should determine who will:

  • Receive the keys

  • Confirm recording and funding

  • Arrange utilities

  • Secure the home

  • Accept deliveries

  • Monitor the property

  • Handle repairs

  • Coordinate movers

  • Receive association information

  • Maintain the yard

  • Address insurance questions

  • Respond to leaks, storm damage, or emergencies

  • Collect mail and important notices

If the home will be vacant, notify the insurance professional and understand any policy conditions involving vacancy, inspections, temperature control, water shutoff, or property monitoring.

If a spouse or dependent will occupy the home, confirm that person has access to closing records, warranties, repair contacts, HOA information, utility accounts, and emergency funds.

A purchase made during military service should also account for future flexibility. What to Prioritize in a Home If You May PCS Again in a Few Years explores why condition, location, maintenance, layout, affordability, and a realistic exit strategy matter when assignments may change.

When Delaying the Closing May Be the Better Option

Remote closing is not always the best answer.

An extension may be appropriate when:

  • The lender has not approved the power of attorney

  • Occupancy questions remain unresolved

  • The inspection requires additional evaluation

  • Repairs are incomplete

  • The appraisal or underwriting file is delayed

  • The buyer cannot securely review the documents

  • Closing funds cannot be transferred safely

  • The final walkthrough cannot be completed properly

  • The buyer’s orders materially change the purpose of the purchase

  • The buyer no longer believes the home supports the assignment

An extension requires seller cooperation unless the contract already gives the buyer the necessary right. It may also affect an interest-rate lock, moving date, seller plans, insurance, prepaid expenses, and other costs.

The buyer should compare the consequences of extending with the risks of forcing the transaction to close before important questions are resolved.

When the Buyer May Need to Reconsider the Purchase

Deployment can reveal that the property no longer fits the buyer’s actual circumstances.

For example:

  • The home will remain vacant for an extended period.

  • The duty station has changed.

  • The anticipated occupant will not move into the property.

  • The household budget has changed.

  • The buyer cannot complete required underwriting.

  • The property needs more hands-on work than expected.

  • The buyer no longer has a reliable local support system.

  • The closing cannot be completed securely.

  • The home makes sense only under the original timeline.

A buyer should not misstate occupancy or conceal changed circumstances to preserve approval.

Whether the buyer may terminate—and what happens to earnest money—depends on the contract, contingencies, deadlines, applicable law, and the specific reason the transaction cannot proceed. Consult the agent, lender, settlement professional, and military legal assistance or another qualified attorney promptly.

Build a Deployment-Ready Closing Checklist

A coordinated closing plan should identify the person responsible for every remaining step.

Before deploying, confirm:

  1. The lender has received and reviewed the orders.

  2. Income and occupancy remain acceptable.

  3. The settlement company knows the buyer will be absent.

  4. Any power of attorney has been approved by every necessary party.

  5. Required VA certifications have been discussed.

  6. Inspection and repair deadlines are assigned.

  7. The appraisal and title status are known.

  8. Homeowners and flood insurance are arranged.

  9. A final-walkthrough representative has been selected.

  10. Closing documents will be delivered securely.

  11. The buyer can review the Closing Disclosure.

  12. Wiring instructions have been independently verified.

  13. The person receiving possession has keys and authority.

  14. Post-closing utilities, maintenance, and emergencies are covered.

  15. A backup plan exists if communication becomes unavailable.

For buyers who need to evaluate properties from another location, How Virtual Tours Help Military Buyers Relocating From Out of State explains how live walkthroughs and local coordination can improve understanding without replacing inspections and due diligence.

Keep the Process Fair Housing-Minded

Deployment planning should remain focused on the buyer’s transaction, financing, occupancy, property needs, and lawful contract terms.

Real estate professionals should provide consistent service without making assumptions about which communities, property types, or housing options a servicemember should choose. The buyer—not the agent—should identify priorities such as commute, price, accessibility, maintenance, property type, proximity to selected destinations, and future flexibility.

Marketing and property recommendations should focus on objective characteristics rather than descriptions of the people who live in an area or claims that a location is appropriate for a particular household type.

Frequently asked questions

Can you close on a house while deployed?

Yes, some deployed buyers can close through a lender- and settlement-approved power of attorney, remote signing process, mail-away package, or another authorized arrangement. The available method depends on the mortgage, lender, title or settlement company, state requirements, and documents being signed. The buyer should arrange the process before departure because a general power of attorney may not contain the authority required for the mortgage and deed-of-trust documents.

Can I use a power of attorney to close on a VA loan while deployed?

VA loans may permit a power of attorney when the document and transaction meet lender and VA requirements. The lender must also complete the applicable verification that the Veteran is alive and, when on active military duty, not missing in action. Because communication may be required close to settlement, buyers should have the document approved early and confirm exactly how the lender will complete the certification. Salyer Wilmoth Homes can help coordinate the real estate timeline with the lender and settlement company, although legal documents should be prepared or reviewed by an appropriate legal professional.

Will deployment affect the VA loan occupancy requirement?

It can affect how occupancy must be documented, but deployment does not automatically make the purchase ineligible. VA states that purchase loans are for homes intended for occupancy and recognizes spouse or dependent occupancy in certain active-duty circumstances. The lender must evaluate the buyer’s actual plan, including who will occupy the home and whether it remains the intended primary residence. Buyers should disclose the deployment and obtain a written explanation from the lender rather than relying on a general rule.

Do military orders automatically let me cancel a home purchase contract?

Do not assume they do. The buyer’s rights depend on the purchase agreement, contingencies, deadlines, applicable law, and the circumstances created by the orders. Federal military protections cover several financial and civil matters, but they should not be treated as an automatic cancellation clause for every pending home purchase. Review the contract promptly with the real estate agent and military legal assistance or another qualified attorney.

What should I do first if I receive deployment orders before closing?

Notify the lender and real estate agent immediately, then include the settlement or title company, insurance professional, and any co-buyer. Confirm whether the loan and occupancy plan remain acceptable, whether the closing date is realistic, and whether a power of attorney or remote signing method is available. Salyer Wilmoth Homes can help organize the property, inspection, walkthrough, and contract steps so the buyer can focus discussions with the lender and legal professionals on financing and signing requirements.

If deployment may interrupt your Coastal Virginia home purchase, let’s organize the transaction early so the lender, settlement company, inspectors, and local representatives are working from the same closing plan.

Michele Salyer, REALTOR®

📞 757-502-3671

🌐 www.salyerwilmothhomes.com

“If you are looking to sell, Call Michele! If you are looking to acquire, I’m your hire!”

Atlantic Sotheby's International Realty

Equal Housing Opportunity


Posted in Buyer Guides